Bill · S. 1639· Senate(119-S-1639)
American Innovation and Jobs Act
- Introduced
- 5/7/2025
- Last activity
- 5/7/2025 — Read twice and referred to the Committee on Finance.
- Sponsored by
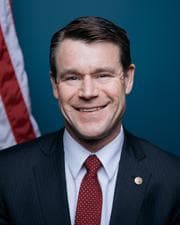
- Todd Young
- Cosponsors
- - 17 - 17
- Introduced
- In Committee
What this bill would do
The "American Innovation and Jobs Act" modifies the Internal Revenue Code of 1986 to provide better tax benefits for research activities. It allows taxpayers to immediately deduct research and experimental expenditures rather than capitalizing them. The bill increases the cap on refundable research credits for new and small businesses over several years. It also extends the eligibility period for certain startups to access these credits. Additionally, it raises the gross receipts threshold for the research credit and creates special rules for qualified small businesses.
Yes· 3 of 16
Would business owners be better off under this?+10
Provides direct tax relief, immediate expensing of R&D, and expanded credits.
Does this make it easier to run a small business?+9
Significantly expands the refundable research credit cap and extends eligibility for startups.
Does this cut taxes for small businesses?+8
Increases refundable credits and provides more favorable percentage rates specifically for qualified small businesses.
The opposite· 3 of 4
Does this raise the taxes companies pay?-5
The bill provides significant tax deductions and credits for businesses, effectively reducing the corporate tax burden for eligible entities.
Does this reduce what the federal government owes?-3
Increased tax credits and immediate expensing likely reduce federal tax revenue, potentially increasing the deficit.
Does this make the government pay for what it commits to?-2
The bill focuses on tax expenditures rather than budgetary constraints.
Who it would affect, and how
Potential Positive Impacts for People
- Immediate Expense Deductions: Taxpayers can treat research or experimental expenditures as expenses to be deducted, which may provide faster tax relief than capitalizing them (Section 2(a)).
- Increased Refundable Credits: The cap on refundable credits for new and small businesses is increased from $250,000 to an "applicable amount" that grows over time, reaching $750,000 by the 2034 taxable year (Section 3(a)).
- Longer Eligibility for Startups: The period for startup date eligibility is extended from a "5-taxable-year period" to an "8-taxable-year period" (Section 3(b)(1)).
- Expanded Access Based on Revenue: The gross receipts test is increased from "$5,000,000" to "$15,000,000," allowing more businesses to qualify for the credit (Section 3(c)(1)).
- Better Terms for Small Businesses: Qualified small businesses receive more favorable percentage rates (20 percent instead of 14 percent, and 10 percent instead of 6 percent) or can disregard years with no research expenses when determining averages (Section 4(a)).
Potential Negative Impacts for People
- Limited Scope of Deductions: Tax benefits do not apply to the acquisition or improvement of land, nor to property used in research that is already subject to depreciation or depletion allowances (Section 2(c)).
- Exclusion of Mineral Exploration: Expenditures used to find the existence, location, extent, or quality of mineral deposits, including oil and gas, are not eligible under this section (Section 2(d)).
- Reasonableness Requirement: The tax benefits only apply to research expenditures that are considered "reasonable under the circumstances," which could lead to disputes over what is reasonable (Section 2(e)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Business Owners+10Good For Billionaires+5Good For High Net Worth Individuals+5Good For Ultra High Net Worth Individuals+5Good For High Income Households+4Good For Young Adults+3Good For Middle Aged+2
- Economy And Finance
- Improves Small Business Support+9Reduces Small Business Taxes+8Improves Economic Growth+6Increases Job Creation+4Increases Corporate Taxes-5Reduces National Debt-3Improves Fiscal Responsibility-2
- Education And Technology
- Increases Scientific Research Funding+6Increases Space Exploration+2
- Healthcare
- Increases Research Funding+3
- National Security And Foreign Policy
- Improves Cybersecurity Defense+2
- Environment Energy And Infrastructure
- Increases Renewable Energy Investment+2Reduces Fossil Fuel Production-2
- 5/7/2025
- Read twice and referred to the Committee on Finance.
- 35 Cosponsors added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Tammy Baldwin
Democrat · Wisconsin
 John Barrasso
Republican · Wyoming
 Ted Budd
Republican · North Carolina
 Katie Britt
Republican · Alabama
 Shelley Capito
Republican · West Virginia
 Christopher Coons
Democrat · Delaware
 Catherine Cortez Masto
Democrat · Nevada
 Steve Daines
Republican · Montana
 Deb Fischer
Republican · Nebraska
 Bill Hagerty
Republican · Tennessee
 Martin Heinrich
Democrat · New Mexico
 Maggie Hassan
Democrat · New Hampshire
 Jon Husted
Republican · Ohio
 Amy Klobuchar
Democrat · Minnesota
 Mark Kelly
Democrat · Arizona
 Angus King
Independent · Maine
 Timothy Kaine
Democrat · Virginia
 John Kennedy
Republican · Louisiana
 Ben Luján
Democrat · New Mexico
 James Lankford
Republican · Oklahoma
 Jerry Moran
Republican · Kansas
 Patty Murray
Democrat · Washington
 Markwayne Mullin
Republican · Oklahoma
 Roger Marshall
Republican · Kansas
 Jon Ossoff
Democrat · Georgia
 Alex Padilla
Democrat · California
 Gary Peters
Democrat · Michigan
 Jacky Rosen
Democrat · Nevada
 Pete Ricketts
Republican · Nebraska
 Jeanne Shaheen
Democrat · New Hampshire
 Elissa Slotkin
Democrat · Michigan
 Tommy Tuberville
Republican · Alabama
 Thomas Tillis
Republican · North Carolina
 Roger Wicker
Republican · Mississippi
 Mark Warner
Democrat · Virginia