Bill · S. 967· Senate(119-S-967)
Downpayment Toward Equity Act of 2025
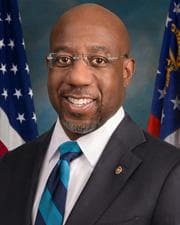
- Introduced
- 3/11/2025
- Last activity
- 3/11/2025 — Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- Sponsored by
- Raphael Warnock
- Cosponsors
- - 6 - 0
- Introduced
- In Committee
What this bill would do
The Downpayment Toward Equity Act of 2025 establishes a program to provide financial assistance to first-generation homebuyers. The Secretary of Housing and Urban Development will distribute grants to States and eligible entities to help these individuals acquire owner-occupied primary residences. This assistance can cover downpayments, closing costs, interest rate reductions, and specific home modifications. The bill aims to address multigenerational inequities and narrow the racial homeownership gap in the United States. It defines specific criteria for qualified homebuyers, eligible homes, and eligible mortgage loans. Finally, it authorizes up to $100,000,000,000 for these grants.
Who it would affect, and how
Potential Positive Impacts for People
-
Financial Assistance for Homebuyers: Qualified homebuyers can receive assistance for downpayment costs, closing costs, costs to reduce mortgage interest rates, or pre-occupancy home modifications for those with disabilities (Section 3(c)).
-
Support for Disadvantaged Individuals: The Secretary may increase the maximum assistance amount for qualified homebuyers who are socially and economically disadvantaged (Section 3(d)(2)(A)).
-
Affordability through Shared Equity: The bill allows for subsidies to make shared equity homes more affordable by discounting the purchase price and preserving affordability for future buyers (Section 3(c)(2)(B)).
-
Access for Foster Care Alumni: The definition of a first-generation homebuyer includes individuals who have been in foster or institutional care (Section 2(5)(B)).
-
Mandatory Homeowner Education: To ensure success, the program requires homebuyers to complete a counseling program regarding the responsibilities and financial management of homeownership (Section 7(a)).
Potential Negative Impacts for People
-
Repayment Requirements: If a homebuyer stops occupying the property as their primary residence before five years, they may be required to repay a proportional amount of the assistance received (Section 5(b)(1)).
-
Income Restrictions: Financial assistance is only available to households whose income does not exceed 120 percent of the area median income, or 140 percent in high-cost areas (Section 4(a)(1)).
-
Home Ownership Limits: Assistance is limited to residential properties consisting of 1 to 4 dwelling units (Section 5(a)(1)).
-
Strict Mortgage Requirements: To receive assistance, the mortgage must meet specific underwriting requirements or be a qualified mortgage (Section 6).
- 6/11/2025
- 1 Cosponsor added.
- 3/11/2025
- Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- 5 Cosponsors added.
- Introduced in Senate
3 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Cory Booker
Democrat · New Jersey
 Timothy Kaine
Democrat · Virginia
 Ben Luján
Democrat · New Mexico
 Alex Padilla
Democrat · California
 Chris Van Hollen
Democrat · Maryland
 Mark Warner
Democrat · Virginia