Bill · S. 4246· Senate(119-S-4246)
Ultra-Millionaire Tax Act of 2026
- Introduced
- 3/26/2026
- Last activity
- 3/26/2026 — Read twice and referred to the Committee on Finance.
- Sponsored by
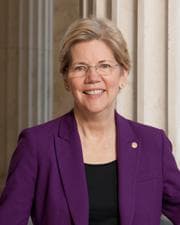
- Elizabeth Warren
- Cosponsors
- - 10 - 0
- Introduced
- In Committee
What this bill would do
The "Ultra-Millionaire Tax Act of 2026" proposes amending the Internal Revenue Code of 1986 to implement a new wealth tax. This tax is based on the net value of an individual's taxable assets at the end of each calendar year. The bill establishes specific tax brackets, with a 2 percent rate for assets above $50,000,000 and a higher applicable percentage for assets exceeding $1,000,000,000. It includes specific rules for married individuals, trusts, and non-residents. The Act also provides for information reporting, enforcement through audits, and significant funding for the IRS.
Yes· 3 of 6
Does this raise taxes on the highest earners?+10
The bill imposes a new wealth tax of 2 percent on assets over $50,000,000 and a higher percentage on assets over $1,000,000,000.
Does this make the government pay for what it commits to?+5
The bill generates significant revenue through a new wealth tax on high-net-worth individuals.
Does this strengthen the Affordable Care Act?+5
The bill's tax rate structure is potentially linked to legislation providing comprehensive health care protection for all residents.
The opposite· 3 of 4
Would people with substantial wealth be better off under this?-10
The bill imposes a multi-bracket wealth tax on individuals with extremely high net worth.
Would billionaires be better off under this?-10
The bill imposes a higher applicable percentage on assets exceeding $1,000,000,000.
Would high-income households be better off under this?-8
The bill imposes a substantial new tax on net assets exceeding $50 million.
Who it would affect, and how
Potential Positive Impacts for People
-
Lower Tax Rate Based on Health Care Legislation: The applicable tax percentage for assets over $1 billion may be set at 3 percent instead of 6 percent if legislation is passed that provides all US residents with comprehensive health care protection and prohibits duplicate benefits (Section 2901(c)).
-
Exclusion of Certain Tangible Personal Property: Tangible personal property valued at $50,000 or less is not included in the taxable assets calculation (Section 2902(b)(1)).
-
Relief for Taxpayers with Financial Hardship: The Secretary may extend the time for paying the wealth tax for up to 5 years if a taxpayer has severe liquidity constraints or if immediate payment would cause undue hardship on an ongoing enterprise (Section 6161(a)).
Potential Negative Impacts for People
-
Tax on High Net Worth Individuals: A tax is imposed on the net value of all taxable assets, including a 2 percent rate for assets between $50,000,000 and $1,000,000,000, plus an applicable percentage for assets over $1,000,000,000 (Section 2901(b)).
-
Increased Tax Rates for Expatriates: Individuals who are covered expatriates are taxed at a higher rate of 40 percent (Section 2903(c)).
-
Heavy Penalties for Asset Undervaluation: Taxpayers may face increased penalties if they provide a substantial wealth tax valuation understatement, which occurs if the claimed value is 65 percent or less of the correct amount (Section 6662(b)).
-
Mandatory Audits: The Secretary is required to annually audit at least 30 percent of taxpayers required to pay the tax (Section 2905).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Low Income Households+3Good For Billionaires-10Good For High Net Worth Individuals-10Good For High Income Households-8Good For Business Owners-4
- Economy And Finance
- Increases Wealthy Taxes+10Improves Fiscal Responsibility+5
- Healthcare
- Increases Affordable Care Act Support+5
- Social Issues And Justice
- Improves Poverty Reduction+3
- Governance And Ideology
- Improves Government Transparency+2
- 3/26/2026
- Read twice and referred to the Committee on Finance.
- 10 Cosponsors added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Tammy Duckworth
Democrat · Illinois
 Mazie Hirono
Democrat · Hawaii
 Edward Markey
Democrat · Massachusetts
 Jeff Merkley
Democrat · Oregon
 Adam Schiff
Democrat · California
 Brian Schatz
Democrat · Hawaii
 Tina Smith
Democrat · Minnesota
 Chris Van Hollen
Democrat · Maryland
 Peter Welch
Democrat · Vermont
 Sheldon Whitehouse
Democrat · Rhode Island