Bill · S. 276· Senate(119-S-276)
Personalized Care Act of 2025
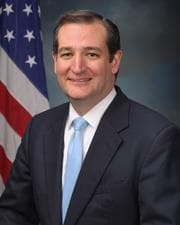
- Introduced
- 1/28/2025
- Last activity
- 1/28/2025 — Read twice and referred to the Committee on Finance.
- Sponsored by
- Ted Cruz
- Cosponsors
- - 2 - 0
- Introduced
- In Committee
What this bill would do
The Personalized Care Act of 2025 aims to amend the Internal Revenue Code to expand and improve health savings accounts. It broadens the definition of an eligible individual to include those covered by various government plans, short term plans, and health care sharing ministries. The bill significantly increases contribution limits for these accounts and allows for payments toward health insurance premiums from the accounts. Additionally, it expands qualified medical expenses to include certain medical care service arrangements and health care sharing ministry costs. Finally, the act reduces the penalty for nonqualified distributions from 20 percent to 10 percent.
Yes· 3 of 13
Would middle-income households be better off under this?+6
The bill significantly increases the maximum contribution limits for HSAs, benefiting middle-income savers.
Would high-income households be better off under this?+6
The massive increase in contribution limits provides significant tax-advantaged savings capacity for high earners.
Does this make health care easier to get in general?+5
The bill expands the definition of eligible individuals and qualified expenses, making it easier to use HSAs for various types of coverage and services.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Expanded Eligibility: The bill expands the definition of an "eligible individual" to include people covered by group or individual health plans, short term limited duration plans, medical indemnity plans, and various government programs like Medicare, Medicaid, and CHIP (Section 2).
-
Increased Savings Capacity: The legislation significantly raises the limits for HSA contributions, increasing the individual limit from $2,250 to $10,800 and the family limit from $4,500 to $29,500 (Section 3).
-
Flexible Premium Payments: Individuals can use their HSA funds to pay for various health plans, insurance, or ministries (Section 4).
-
New Qualified Medical Expenses: The bill allows for the use of HSA funds for "medical care service arrangements," which include periodic fees for a defined set of services or prepaid amounts for various medical needs (Section 5).
-
Support for Sharing Ministries: For members of a health care sharing ministry, the bill allows for the use of HSA funds to pay for the sharing of medical expenses and administrative fees (Section 8).
-
Reduced Penalties: The penalty for taking nonqualified distributions from an HSA is reduced from 20 percent to 10 percent (Section 7).
Potential Negative Impacts for People
- Note: The provided text does not explicitly list negative consequences or burdens for individuals or groups of people.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For High Income Households+6Good For Middle Class Households+6Good For Seniors+4Good For Veterans+4Good For Low Income Households+3Good For Native Americans+3
- Healthcare
- Improves Healthcare Access+5Increases Medicaid Funding+3Increases Medicare Funding+3
- Economy And Finance
- Reduces Middle Class Taxes+5Improves Economic Growth+2
- Social Issues And Justice
- Improves Disability Rights+2Improves Poverty Reduction+2
- 1/8/2026
- 1 Cosponsor added.
- 1/28/2025
- Read twice and referred to the Committee on Finance.
- 1 Cosponsor added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Roger Marshall
Republican · Kansas
 Ashley Moody
Republican · Florida