Bill · S. 2758· Senate(119-S-2758)
Freight RAILCAR Act of 2025
- Introduced
- 9/10/2025
- Last activity
- 9/10/2025 — Read twice and referred to the Committee on Finance.
- Sponsored by
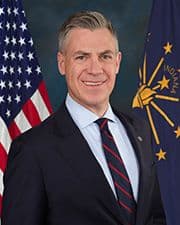
- Jim Banks
- Cosponsors
- - 0 - 2
- Introduced
- In Committee
What this bill would do
The Freight RAILCAR Act of 2025 aims to amend the Internal Revenue Code of 1986 to encourage the replacement or modernization of inefficient freight railcars. It establishes a new tax credit equal to 10 percent of a taxpayer's freight railcar fleet modernization expenses. This credit applies to qualifying newly built replacement railcars and qualified modernization expenditures. To prevent excessive use, the credit is limited to 1,000 qualified freight railcars per taxpayer per taxable year. The legislation includes specific definitions for qualified railcars, modernized equipment, and qualified facilities. Additionally, the act requires a report to Congress regarding the credit's activity after three years.
Yes· 3 of 6
Does this cut taxes for small businesses?+5
The bill provides a 10 percent tax credit for freight railcar fleet modernization expenses to encourage equipment replacement.
Would business owners be better off under this?+5
The bill offers a significant tax credit to businesses involved in freight rail operations for asset modernization.
Is this likely to create jobs?+3
The tax credit for new railcar construction and modernization may stimulate activity in the railcar manufacturing sector.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Tax Incentives for Modernization: Taxpayers can receive a credit equal to 10 percent of their freight railcar fleet modernization expenses, which encourages the replacement of outdated equipment (Section 2(a)).
-
Increased Capacity and Performance: The bill provides for "significant improvement" through increased capacity of at least 8 percent or by meeting specific performance and design standards, such as the Association of American Railroads Standard S-286 (Section 2(c)(4)(B)).
-
Encouraging New Equipment: The credit applies to the basis of any qualified newly built replacement railcar placed in service, provided it replaces two scrapped railcars (Section 2(c)(3)).
Potential Negative Impacts for People
-
Limits on Credit Usage: Taxpayers are restricted from claiming the credit for more than 1,000 qualified freight railcars per taxable year (Section 2(b)).
-
Reduction in Tax Basis: If a credit is allowed for a qualified freight railcar, the basis of that railcar must be reduced by the amount of the credit (Section 2(d)(2)).
-
Expiration of Benefits: The credit is not permanent, as it shall not apply to qualifying amounts after a date that is three years after the enactment of the section (Section 2(e)).
-
Exclusion of Certain Entities: Taxpayers that would be ineligible for a contract or subcontract under 49 U.S.C. 5323(u) are prohibited from receiving the credit (Section 2(d)(5)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Reduces Small Business Taxes+5Improves Small Business Support+3Increases Job Creation+3Improves Economic Growth+2
- Demographic And Interest Groups
- Good For Business Owners+5
- Environment Energy And Infrastructure
- Improves Roads And Bridges+2
- 5/13/2026
- 1 Cosponsor added.
- 9/10/2025
- Read twice and referred to the Committee on Finance.
- 1 Cosponsor added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Christopher Coons
Democrat · Delaware
 Jeff Merkley
Democrat · Oregon