Bill · S. 1979· Senate(119-S-1979)
Rare Earth Magnet Security Act of 2025
- Introduced
- 6/5/2025
- Last activity
- 6/5/2025 — Read twice and referred to the Committee on Finance.
- Sponsored by
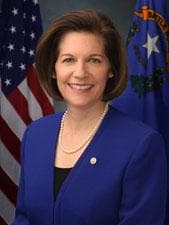
- Catherine Cortez Masto
- Cosponsors
- - 0 - 2
- Introduced
- In Committee
What this bill would do
The Rare Earth Magnet Security Act of 2025 aims to amend the Internal Revenue Code of 1986 to establish a new tax credit. This credit is intended for the domestic production of high-performance rare earth magnets. Taxpayers can receive $20 per kilogram produced in the United States, or $30 per kilogram if at least 90 percent of the component materials are also produced within the country. The bill includes a phase-out schedule that begins after December 31, 2034. Additionally, the act places restrictions on sourcing materials from non-allied foreign nations.
Yes· 3 of 6
Is this likely to create jobs?+5
The production tax credit incentivizes domestic manufacturing which can lead to increased job creation in the magnet industry.
Would business owners be better off under this?+5
The tax credit provides a direct financial incentive for domestic manufacturing businesses.
Does this put more money into wind, solar and other renewable power?+4
Rare earth magnets are critical components for many renewable energy technologies like wind turbines.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Increased Financial Incentives for Domestic Production: Taxpayers can receive a credit of $20 per kilogram of rare earth magnets produced in the U.S., or a higher credit of $30 per kilogram if 90 percent of the component materials are produced domestically (Section 2(a)(1) and Section 2(b)(1)).
-
Support for National Security Through Manufacturing: The Secretary has the authority to allow credits for magnets that do not meet specific coercivity requirements if they are produced by an "eligible manufacturer" who commits to a domestic facility with national security merit (Section 2(d)(3)).
-
Flexible Payment Options for Businesses: Taxpayers can elect to receive an elective payment for the portion of the credit they are owed (Section 2(e)(1)).
-
Use of Seized Materials: The bill allows for the use of component materials seized from non-allied foreign nations during wartime by Ukraine or an allied country to qualify for the credit (Section 2(d)(1)(C)).
Potential Negative Impacts for People
-
Phasing Out of Financial Support: The credit amount will decrease over time, reducing to 70 percent in 2035, 35 percent in 2036 and 2037, and reaching 0 percent after December 31, 2037 (Section 2(b)(2)).
-
Strict Sourcing Restrictions: No credit is allowed if any component rare earth material used in the magnet is produced in a non-allied foreign nation, which may impact manufacturing processes (Section 2(d)(1)(A)).
-
Increased Administrative Requirements: The Secretary may require specific information or registration from taxpayers to prevent fraud or duplication when electing to treat sales to related persons as sales to unrelated persons (Section 2(a)(2)(B)(ii)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Increases Job Creation+5Improves Economic Growth+3
- Demographic And Interest Groups
- Good For Business Owners+5
- Environment Energy And Infrastructure
- Increases Renewable Energy Investment+4
- National Security And Foreign Policy
- Improves International Alliances+3
- Governance And Ideology
- Increases Federal Power+2
- 6/5/2025
- Read twice and referred to the Committee on Finance.
- 2 Cosponsors added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Lindsey Graham
Republican · South Carolina
 Markwayne Mullin
Republican · Oklahoma