Bill · S. 187· Senate(119-S-187)
ALIGN Act
- Introduced
- 1/22/2025
- Last activity
- 1/22/2025 — Read twice and referred to the Committee on Finance.
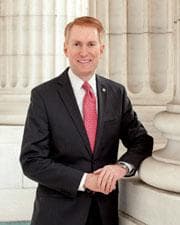
- Sponsored by
- James Lankford
- Cosponsors
- - 13 - 0
- Introduced
- In Committee
What this bill would do
This bill, known as the "ALIGN Act," aims to amend the Internal Revenue Code of 1986. It seeks to permanently allow for full expensing of qualified property. This means the applicable percentage for property placed in service after September 27, 2017, would be set at 100 percent. The legislation also includes conforming amendments to various sections of the tax code. These changes impact how property and plants are treated for tax purposes.
Yes· 3 of 8
Would business owners be better off under this?+6
The bill directly benefits business owners by allowing them to immediately deduct the cost of qualified property investments.
Would farmers be better off under this?+5
The amendment regarding plant grafting specifically benefits agricultural investments.
Does this cut taxes for small businesses?+5
The bill allows for full expensing of qualified property, which provides immediate tax deductions for business investments.
The opposite
Does this reduce what the federal government spends?-2
The permanent implementation of full expensing likely reduces federal tax revenue.
Does this cut the tax on profits from selling investments?-1
By prioritizing immediate expensing of business assets, the bill focuses on investment deductions rather than capital gains reductions.
Who it would affect, and how
Potential Positive Impacts for People
-
Permanent Full Expensing: The bill changes the "applicable percentage" to 100 percent for property placed in service after September 27, 2017, allowing for a tax deduction at the time an investment in qualified property is made (Section 2(a)).
-
Changes to Plant Treatment: The bill amends the language regarding plants to state that the 100 percent rate applies to a plant that is "planted or grafted," removing previous time restrictions (Section 2(b)(1)(A)(ii)).
Potential Negative Impacts for People
- No negative impacts are explicitly stated in the provided text.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Business Owners+6Good For Farmers+5Good For High Net Worth Individuals+3
- Economy And Finance
- Improves Small Business Support+5Reduces Small Business Taxes+5Improves Economic Growth+4Increases Job Creation+3Reduces Government Spending-2Reduces Capital Gains Tax-1
- Environment Energy And Infrastructure
- Increases Renewable Energy Investment+2
- 4/10/2025
- 1 Cosponsor added.
- 2/13/2025
- 1 Cosponsor added.
- 2/5/2025
- 1 Cosponsor added.
- 2/4/2025
- 1 Cosponsor added.
- 1/22/2025
- Read twice and referred to the Committee on Finance.
- 9 Cosponsors added.
- Introduced in Senate
4 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 John Boozman
Republican · Arkansas
 Marsha Blackburn
Republican · Tennessee
 John Barrasso
Republican · Wyoming
 Shelley Capito
Republican · West Virginia
 Steve Daines
Republican · Montana
 Chuck Grassley
Republican · Iowa
 John Hoeven
Republican · North Dakota
 Mike Lee
Republican · Utah
 Roger Marshall
Republican · Kansas
 James Risch
Republican · Idaho
 Pete Ricketts
Republican · Nebraska
 Tim Sheehy
Republican · Montana
 Todd Young
Republican · Indiana