Bill · S. 1458· Senate(119-S-1458)
Adoption Tax Credit Refundability Act of 2025
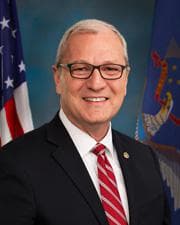
- Introduced
- 4/10/2025
- Last activity
- 4/10/2025 — Read twice and referred to the Committee on Finance.
- Sponsored by
- Kevin Cramer
- Cosponsors
- - 6 - 11
- Introduced
- In Committee
What this bill would do
This bill is called the Adoption Tax Credit Refundability Act of 2025. It changes the Internal Revenue Code of 1986 to make the adoption tax credit a refundable credit. The bill moves the adoption tax credit into the section of the tax code that deals with refundable credits. It also requires regulations and guidance to provide a standardized third-party affidavit to verify legal adoptions. These changes apply to taxable years beginning after December 31, 2024. Any excess credit from the year before the amendments apply is added to the taxpayer's credit for the first new taxable year.
Yes· 3 of 4
Would households on low incomes be better off under this?+7
Making the credit refundable provides essential financial support to low-income families who cannot use non-refundable credits.
Would children be better off under this?+5
The bill supports families adopting children, which can lead to better outcomes for children in the adoption system.
Would middle-income households be better off under this?+5
The refundability allows middle-class taxpayers to realize the full benefit of the adoption credit.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Section 2(a) makes the adoption tax credit refundable by moving it to the subpart of the tax code relating to refundable credits. This is positive because it allows individuals to receive the full benefit of the credit even if it exceeds their tax liability.
-
Section 2(b) adds a provision for a standardized third-party affidavit to verify a legal adoption or an adoption involving a child with special needs. This is positive because it helps streamline and clarify the verification process for families going through adoptions.
-
Section 2(d) creates a transitional rule that treats any previous excess credit carryforward as a refundable credit for the first taxable year the amendments apply. This is positive because it ensures people do not lose the credit value they built up under the old rules.
Potential Negative Impacts for People
- The provided text does not contain any specific provisions outlining negative consequences or burdens for individuals or groups of people.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Low Income Households+7Good For Children+5Good For Middle Class Households+5
- Economy And Finance
- Reduces Middle Class Taxes+5
- 5/7/2025
- 1 Cosponsor added.
- 4/30/2025
- 1 Cosponsor added.
- 4/10/2025
- Read twice and referred to the Committee on Finance.
- 16 Cosponsors added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Marsha Blackburn
Republican · Tennessee
 Shelley Capito
Republican · West Virginia
 Tammy Duckworth
Democrat · Illinois
 John Fetterman
Democrat · Pennsylvania
 Josh Hawley
Republican · Missouri
 Amy Klobuchar
Democrat · Minnesota
 Mark Kelly
Democrat · Arizona
 Angus King
Independent · Maine
 Timothy Kaine
Democrat · Virginia
 Ben Luján
Democrat · New Mexico
 James Lankford
Republican · Oklahoma
 Jeff Merkley
Democrat · Oregon
 Jacky Rosen
Democrat · Nevada
 Tim Scott
Republican · South Carolina
 Chris Van Hollen
Democrat · Maryland
 Roger Wicker
Republican · Mississippi
 Mark Warner
Democrat · Virginia
 Elizabeth Warren
Democrat · Massachusetts