Bill · S. 1443· Senate(119-S-1443)
Mobile Workforce State Income Tax Simplification Act of 2025
- Introduced
- 4/10/2025
- Last activity
- 4/10/2025 — Read twice and referred to the Committee on Finance. (text: CR S2566-2567)
- Sponsored by
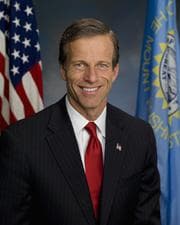
- John Thune
- Cosponsors
- - 0 - 2
- Introduced
- In Committee
What this bill would do
This bill is called the Mobile Workforce State Income Tax Simplification Act of 2025. It limits the power of states to tax the income of employees who work in more than one state. Under the bill, wages earned by an employee working in multiple states can only be taxed by the employee's resident state and any state where the employee works for more than 30 days in a calendar year. It also stops states from requiring income tax withholding and reporting unless the employee actually meets that tax requirement. Additionally, the bill outlines operating rules for employers relying on employee time determinations or tracking systems. Finally, certain workers like professional athletes, professional entertainers, and public figures are excluded from these rules.
Yes· 3 of 5
Does this make it easier to do business across state lines?+5
The bill limits state authority over employee income, facilitating easier cross-state movement for work.
Does this cut taxes for middle-income families?+4
The bill simplifies and potentially reduces the tax burden for mobile workers by limiting which states can tax their income.
Would middle-income households be better off under this?+3
Mobile workers in this bracket benefit from simplified tax reporting and potential savings.
The opposite
Does this leave more decisions to the states?-5
The bill reduces the ability of states to levy income taxes on residents who work within their borders.
Who it would affect, and how
Potential Positive Impacts for People
-
Section 2(a): Employees who perform duties in more than one state benefit because their wages cannot be taxed by a nonresident state unless they are present and working in that state for more than 30 days during the calendar year. This protects traveling workers from dealing with multiple state taxes for short trips.
-
Section 2(b): Individuals benefit because wages earned in any calendar year are not subject to State income tax withholding and reporting requirements unless the employee is actually subject to income tax in that state under the 30-day rule. This saves workers from unnecessary tax paperwork.
-
Section 2(c)(1): Employers and employees benefit because an employer is allowed to rely on an employee's annual determination of expected time spent working in different states, as long as there is no actual fraud or collusion to evade taxes. This makes reporting simpler for everyday workers.
Potential Negative Impacts for People
- Section 2(d)(2): Professional athletes, professional entertainers, qualified production employees, and certain public figures are specifically excluded from the definition of an employee under the bill. This means these specific groups do not receive the tax limitations provided to other workers, leaving them subject to the existing state tax rules.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Business Owners+3Good For Middle Class Households+3
- Economy And Finance
- Reduces Middle Class Taxes+4
- Governance And Ideology
- Improves Interstate Commerce+5Increases Federal Power+2Increase States Rights-5
- 7/21/2026
- 1 Cosponsor added.
- 4/10/2025
- Read twice and referred to the Committee on Finance. (text: CR S2566-2567)
- 1 Cosponsor added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Catherine Cortez Masto
Democrat · Nevada
 Jacky Rosen
Democrat · Nevada