Bill · H.R. 5336· House(119-HR-5336)
Equal Tax Act
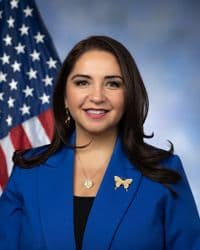
- Introduced
- 9/11/2025
- Last activity
- 9/11/2025 — Referred to the House Committee on Ways and Means.
- Sponsored by
- Delia Ramirez
- Cosponsors
- - 17 - 0
- Introduced
- In Committee
What this bill would do
This bill proposes changes to how capital gains, dividends, and certain incomes are taxed under the Internal Revenue Code of 1986. It limits preferential tax rates for dividends and capital gains to incomes of $1,000,000 or less as outlined in Section 2. The legislation treats property transferred by gift or at death as if it were sold for its fair market value, with specific exceptions detailed in Section 3. Section 4 provides an exclusion of certain amounts of realized capital gain from transfers at death. Additionally, Section 6 allows for a 5-year installment payment plan for capital gains tax owed due to a taxpayer's death. Finally, Section 7 and Section 8 place limitations on like-kind exchanges and the deduction for qualified business income.
Yes· 3 of 10
Does this raise taxes on the highest earners?+8
The bill limits preferential tax rates for dividends and capital gains to incomes of $1,000,000 or less, effectively increasing taxes on high-income earners.
Does this reduce what the federal government owes?+5
By eliminating certain capital gains preferences and taxing unrealized gains at death, federal revenues are projected to increase.
Does this make the government pay for what it commits to?+4
The legislation closes tax loopholes related to estate transfers and capital gains preferences.
The opposite· 3 of 13
Would the very wealthiest people be better off under this?-10
Ultra-high-net-worth individuals face severe tax increases due to the removal of capital gains preferences above $1,000,000 and deemed realization at death.
Would billionaires be better off under this?-10
Billionaires are directly targeted by the removal of capital asset tax loopholes and the imposition of realization rules at death.
Would people with substantial wealth be better off under this?-9
High-net-worth individuals are heavily impacted by the elimination of step-up in basis and taxes on gifts and bequests.
Who it would affect, and how
Potential Positive Impacts for People
-
Exclusion for Capital Gains at Death: Under Section 4 (Section 139J(a)(1)), gross income does not include up to $1,000,000 of net capital gain from transfers at death. This provision is positive because it shields a substantial amount of inherited assets from immediate heavy taxation for everyday families.
-
Relief for Family Farms and Businesses: Section 4 (Section 139J(a)(2)) excludes 50 percent of capital gains exceeding $1,000,000 for qualifying family farms or businesses transferred at death, provided they continue operating. This benefits heirs who wish to keep a family farm or business running without being forced to sell it to pay taxes.
-
Installment Payments for Death-Related Capital Gains: Section 6 (Section 6168(a)(1)) allows taxpayers to pay capital gains tax triggered by a death in two to five equal installments. This is beneficial because it eases the immediate financial shock on families inheriting eligible property by spreading out the tax payments.
-
Spousal Transfer Protections: Section 3 (Section 1261(b)(1)) ensures that property transferred to a spouse or surviving spouse is exempt from being treated as a sale upon death or gift. This protects surviving spouses from sudden tax burdens during a difficult time.
Potential Negative Impacts for People
-
Taxes Triggered by Gifts and Death: Section 3 (Section 1261(a)) treats any property transferred by gift or at death as sold for its fair market value. This could place a heavy tax burden on individuals receiving gifts or inheritances by forcing them to pay capital gains taxes on assets before they even sell them.
-
Limits on Like-Kind Exchanges: Section 7 (Section 1031(a)(4)) places annual and aggregate limitations on the amount of gain excluded from recognition during real estate exchanges. This may burden real estate owners and investors who previously deferred taxes on larger property exchanges.
-
Restrictions on Qualified Business Income Deductions: Section 8 limits the deduction for qualified business income so that it applies only to taxable income that does not exceed $1,000,000. This could negatively impact business owners making over this threshold by reducing their tax deductions.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Farmers+3Good For Low Income Households+2Good For Middle Class Households+2Good For Rural Residents+2Good For Billionaires-10Good For Ultra High Net Worth Individuals-10Good For High Net Worth Individuals-9Good For High Income Households-8Good For Business Owners-5Good For Retirees-3Good For Seniors-3
- Governance And Ideology
- Increases Federal Power+3Improves Government Transparency+2Improves Privacy Rights-2
- Social Issues And Justice
- Improves Affordable Housing-3
- Environment Energy And Infrastructure
- Improves Rural Development+2
- Economy And Finance
- Increases Wealthy Taxes+8Reduces National Debt+5Improves Fiscal Responsibility+4Reduces Capital Gains Tax-7Reduces Small Business Taxes-4Improves Small Business Support-3Improves Economic Growth-2
- 6/23/2026
- 1 Cosponsor added.
- 3/26/2026
- 1 Cosponsor added.
- 2/4/2026
- 1 Cosponsor added.
- 12/17/2025
- 1 Cosponsor added.
- 11/25/2025
- 1 Cosponsor added.
- 10/31/2025
- 1 Cosponsor added.
- 9/15/2025
- 2 Cosponsors added.
- 9/11/2025
- Referred to the House Committee on Ways and Means.
- 9 Cosponsors added.
- Introduced in House
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Yassamin Ansari
Democrat · Arizona
 Greg Casar
Democrat · Texas
 Christopher Deluzio
Democrat · Pennsylvania
 Adriano Espaillat
Democrat · New York
 Jesús García
Democrat · Illinois
 Daniel Goldman
Democrat · New York
 Pramila Jayapal
Democrat · Washington
 James McGovern
Democrat · Massachusetts
 Betty McCollum
Democrat · Minnesota
 Analilia Mejia
Democrat · New Jersey
 Eleanor Norton
Democrat · District of Columbia
 Ilhan Omar
Democrat · Minnesota
 Janice Schakowsky
Democrat · Illinois
 Melanie Stansbury
Democrat · New Mexico
 Rashida Tlaib
Democrat · Michigan
 Shri Thanedar
Democrat · Michigan
 Bonnie Watson Coleman
Democrat · New Jersey