Bill · S. 4122· Senate(119-S-4122)
Equal Tax Act
- Introduced
- 3/17/2026
- Last activity
- 3/17/2026 — Read twice and referred to the Committee on Finance.
- Sponsored by
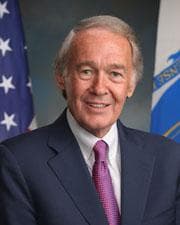
- Edward Markey
- Cosponsors
- - 2 - 0
- Introduced
- In Committee
What this bill would do
The Equal Tax Act aims to make the tax treatment of capital gains and earned income the same. It limits preferential tax rates for dividends and capital gains to taxpayers with incomes of $1,000,000 or less. The bill treats most property transferred by gift or at death as if it were sold at fair market value, though some exceptions and exclusions exist. It introduces new reporting requirements for gifts and bequests and provides a 5-year installment payment plan for taxes resulting from death. Additionally, it limits like-kind exchanges for real estate and restricts the deduction for qualified business income to incomes under $1,000,000.
Yes· 3 of 7
Does this raise taxes on the highest earners?+8
Eliminates preferential capital gains rates for those earning over $1,000,000.
Does this reduce what the federal government owes?+5
Likely increases federal revenue through higher taxes on high earners and capital gains.
Does this make the government pay for what it commits to?+3
Increases tax revenue to potentially reduce deficits.
The opposite· 3 of 13
Would the very wealthiest people be better off under this?-10
Severely impacts wealth transfer strategies and high-value asset appreciation.
Would billionaires be better off under this?-10
Directly targets high-value capital gains and estates.
Would people with substantial wealth be better off under this?-9
Significant increase in tax burden via capital gains equalization and gift/death realization.
Who it would affect, and how
Potential Positive Impacts for People
-
Tax Relief for Lower and Middle Income Earners: Preferential rates for dividends and capital gains remain available for those with taxable income of $1,000,000 or less (Section 2(a)).
-
Protection for Family Farms and Businesses: Gains from the transfer of qualifying family farms or businesses by gift or bequest are not counted toward the $1,000,000 income limit for preferential rates (Section 2(b)).
-
Exclusions for Death Transfers: Gross income will not include the first $1,000,000 of net capital gain from transfers at death (Section 4(a)(1)).
-
Support for Family Business Continuity: 50 percent of capital gains exceeding $1,000,000 from the transfer of a certified qualifying family farm or business at death are excluded from gross income (Section 4(a)(2)).
-
Flexible Tax Payments After Death: Taxpayers can elect to pay taxes on eligible property recognized at death in installments over 2 to 5 years (Section 6(a)(1)).
-
Reduced Interest Rates for Death-Related Taxes: Taxes paid via the installment plan for gains realized by reason of death will be charged interest at 45 percent of the standard annual rate (Section 6(b)).
Potential Negative Impacts for People
-
Increased Tax Burden for High Earners: Taxpayers with incomes exceeding $1,000,000 lose the preferential tax rates for dividends and capital gains (Section 2(a)).
-
Taxation of Gifts and Inheritances: Most property transferred by gift or at death is now treated as sold at fair market value, potentially triggering immediate tax liabilities (Section 3(a)(1)).
-
Limits on Real Estate Tax Deferral: The amount of gain excluded from like-kind exchanges for non-qualified property is limited to $500,000 annually and $1,000,000 in total (Section 7(a)).
-
Restrictions on Business Deductions: The deduction for qualified business income is limited to taxpayers with taxable income not exceeding $1,000,000 (Section 8(a)(1)).
-
Increased Reporting Requirements: Individuals making gifts or executors handling transfers at death must now furnish the Secretary with the recipient's identity, property descriptions, and fair market values (Section 5(a)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Farmers+2Good For Middle Class Households+2Good For Rural Residents+1Good For Billionaires-10Good For Ultra High Net Worth Individuals-10Good For High Net Worth Individuals-9Good For High Income Households-8Good For Business Owners-4Good For Seniors-4Good For Retirees-3
- Economy And Finance
- Increases Wealthy Taxes+8Reduces National Debt+5Improves Fiscal Responsibility+3Reduces Capital Gains Tax-7Reduces Estate Tax-5Reduces Small Business Taxes-3Improves Economic Growth-2Improves Small Business Support-2
- Governance And Ideology
- Increases Federal Power+2Improves Privacy Rights-3
- 3/17/2026
- Read twice and referred to the Committee on Finance.
- 3 Cosponsors added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Cory Booker
Democrat · New Jersey
 Jeff Merkley
Democrat · Oregon
 Bernie Sanders
Independent · Vermont