Bill · H.R. 1091· House(119-HR-1091)
Carried Interest Fairness Act of 2025
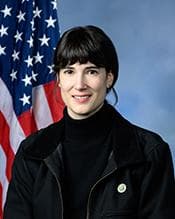
- Introduced
- 2/6/2025
- Last activity
- 2/6/2025 — Referred to the House Committee on Ways and Means.
- Sponsored by
- Marie Perez
- Cosponsors
- - 2 - 0
- Introduced
- In Committee
What this bill would do
The "Carried Interest Fairness Act of 2025" aims to change how personal service income is taxed when earned through pass-thru entities. It specifically targets investment management services provided to investment partnerships. The bill reclassifies certain net capital gains and losses as ordinary income and loss. It also updates rules regarding the transfer of partnership interests and the disposition of those interests. Additionally, the Act modifies how these earnings are treated for self-employment and social security purposes. These changes are intended to ensure proper tax treatment for specific types of partnership income.
Yes· 3 of 4
Does this raise taxes on the highest earners?+7
The bill increases the tax burden on investment managers by reclassifying capital gains as ordinary income.
Does this reduce what the federal government owes?+2
Increasing taxes on high-earning investment managers may contribute to federal revenue increases.
Does this make the government pay for what it commits to?+2
The bill aims to ensure proper tax treatment of income to optimize revenue collection.
The opposite· 3 of 8
Would high-income households be better off under this?-7
The bill negatively impacts high-income individuals engaged in investment management services.
Would people with substantial wealth be better off under this?-7
High net worth individuals in investment management face higher taxes and penalties.
Would the very wealthiest people be better off under this?-7
The bill specifically targets highly compensated investment managers.
Who it would affect, and how
Potential Positive Impacts for People
-
Reclassification of Income: Certain amounts equal to net capital gain for investment services partnership interests will be treated as ordinary income (Section 3(a)(1)(A)).
-
Reclassification of Losses: Certain amounts equal to net capital loss for investment services partnership interests will be treated as ordinary loss (Section 3(a)(1)(B)).
-
Treatment of Dispositions: Gains on the disposition of an investment services partnership interest will be treated as ordinary income (Section 3(b)(1)(A)).
-
Inclusion in Self-Employment Earnings: Investment services partnership income or loss will be taken into account when determining net earnings from self-employment (Section 3(e)(1)(A)).
Potential Negative Impacts for People
-
Loss of Capital Gain Treatment: Net capital gains associated with investment services partnership interests will be treated as ordinary income rather than capital gains (Section 3(a)(1)(A)).
-
Limitation on Loss Deductions: The amount of ordinary loss that can be treated as a net capital loss is limited to the excess of ordinary income over ordinary loss for preceding years (Section 3(a)(1)(B)).
-
Dividend Reclassification: Dividends allocated to an investment services partnership interest will not be treated as qualified dividend income (Section 3(a)(5)).
-
Small Business Stock Restriction: Section 1202 will not apply to gains from the sale of qualified small business stock allocated to an investment services partnership interest (Section 3(a)(6)).
-
Increased Penalties: The penalty for certain underpayments related to these rules may increase from 20 percent to 40 percent (Section 3(d)(2)(A)).
-
Stricter Reasonable Cause Standards: The "reasonable cause" exception for underpayments is modified to require that the taxpayer has adequate disclosure, substantial authority, and a reasonable belief that the treatment was more likely than not to be proper (Section 3(d)(3)(A)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For High Income Households-7Good For High Net Worth Individuals-7Good For Ultra High Net Worth Individuals-7Good For Billionaires-5Good For Business Owners-3
- Economy And Finance
- Increases Wealthy Taxes+7Improves Fiscal Responsibility+2Reduces National Debt+2Reduces Capital Gains Tax-6Improves Economic Growth-1
- Governance And Ideology
- Increases Federal Power+2Improves Due Process-2
- 5/20/2025
- 1 Cosponsor added.
- 2/6/2025
- Referred to the House Committee on Ways and Means.
- 1 Cosponsor added.
- Introduced in House
4 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Donald Beyer
Democrat · Virginia
 Zoe Lofgren
Democrat · California