Bill · H.R. 3275· House(119-HR-3275)
Small Business Tax Relief Act
- Introduced
- 5/8/2025
- Last activity
- 5/8/2025 — Referred to the House Committee on Ways and Means.
- Sponsored by
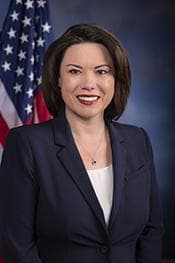
- Angie Craig
- Cosponsors
- None
- Introduced
- In Committee
What this bill would do
The Small Business Tax Relief Act aims to amend the Internal Revenue Code of 1986. The bill proposes a graduated corporate tax rate to provide relief for small businesses with taxable income under $5,000,000. It also seeks to close the carried interest loophole by modifying the treatment of partnership interests and investment management services. Additionally, the Act includes an enhanced deduction for certain lower-income self-employed individuals. Finally, it increases the excise tax on the repurchase of corporate stock.
Yes· 3 of 8
Does this cut taxes for small businesses?+7
The bill implements a graduated tax rate of 18 percent for corporations with income up to $400,000.
Does this make it easier to run a small business?+7
Small businesses with income under $5,000,000 receive significant tax relief through a graduated rate.
Does this raise taxes on the highest earners?+6
The bill closes the carried interest loophole, treating certain partnership gains as ordinary income.
The opposite
Does this cut the tax on profits from selling investments?-5
The bill recharacterizes certain net capital gains as ordinary income for investment management services.
Would high-income households be better off under this?-5
The bill negatively impacts high-income investment managers by reclassifying capital gains as ordinary income.
Would people with substantial wealth be better off under this?-4
The increase in the excise tax on stock repurchases and the carried interest changes affect high-net-worth investors.
Who it would affect, and how
Potential Positive Impacts for People
-
Tax Relief for Small Businesses: Corporations with taxable income not exceeding $5,000,000 would pay 18 percent on income up to $400,000 and 21 percent on income above that amount (Section 2).
-
Enhanced Deductions for Individuals: Self-employed individuals with an adjusted gross income of less than $400,000 would see an enhanced deduction, where the deduction is three quarters of the taxes imposed rather than one-half (Section 5).
Potential Negative Impacts for People
-
Tax Changes for Investment Management: Partners providing investment management services to partnerships would see certain net capital gains and losses treated as ordinary income and loss (Section 4).
-
Increased Tax on Stock Repurchases: The excise tax on the repurchase of corporate stock would increase from 1 percent to 1.5 percent (Section 6).
-
Increased Penalties: There is an increase in the penalty for certain underpayments related to the avoidance of the new rules, raising the rate from 20 percent to 40 percent (Section 4).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Improves Small Business Support+7Reduces Small Business Taxes+7Increases Wealthy Taxes+6Improves Economic Growth+3Reduces Middle Class Taxes+3Improves Fiscal Responsibility+2Reduces Capital Gains Tax-5
- Demographic And Interest Groups
- Good For Business Owners+5Good For Middle Class Households+4Good For High Income Households-5Good For High Net Worth Individuals-4
- 5/8/2025
- Referred to the House Committee on Ways and Means.
- Introduced in House
3 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.