Bill · S. 3156· Senate(119-S-3156)
Federal Worker Mortgage Forbearance Act
- Introduced
- 11/7/2025
- Last activity
- 11/7/2025 — Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- Sponsored by
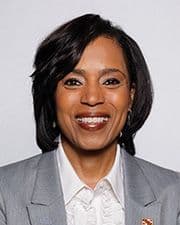
- Angela Alsobrooks
- Cosponsors
- - 3 - 0
- Introduced
- In Committee
What this bill would do
The Federal Worker Mortgage Forbearance Act allows certain federal employees and contractors to request mortgage forbearance during a lapse in appropriations. Eligible individuals with federally backed mortgage loans can receive a 90-day forbearance period by affirming they face financial hardship. The bill prohibits lenders from requiring lump-sum payments after the forbearance ends and prevents additional fees or interest from accruing beyond the original contract terms. It also ensures that these accommodations are reported correctly to credit bureaus.
Yes· 3 of 9
Would households on low incomes be better off under this?+6
Prevents catastrophic financial loss for low-income federal workers during pay lapses.
Would middle-income households be better off under this?+6
Provides a safety net for middle-class federal employees to maintain housing during shutdowns.
Would people in middle age be better off under this?+5
Provides mortgage security for federal employees who are likely to be homeowners.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Mortgage Relief During Pay Lapses: Covered individuals can request a 90-day forbearance on federally backed mortgage loans if they experience financial hardship due to a lapse in appropriations, regardless of whether they are already delinquent. (Section 2(b)(1)-(2))
-
Protection from Extra Costs: The bill prevents the accrual of extra fees, penalties, or interest during the forbearance period beyond what was originally scheduled in the mortgage contract. (Section 2(b)(4))
-
Flexible Repayment: Servicers are prohibited from demanding a lump-sum payment for the missed payments once the forbearance period ends. (Section 2(b)(5))
-
Credit Score Protection: The bill requires furnishers to report the credit account as current if the consumer is not required to make payments under the forbearance agreement. (Section 2(c))
-
Support for Contractors: The bill extends eligibility to contractors who provide support to agency employees and are unable to provide those services during a lapse in appropriations. (Section 2(a)(2))
Potential Negative Impacts for People
-
Criminal Penalties: Individuals who knowingly make false statements when requesting forbearance can be charged with a crime under section 1014 of title 18, United States Code. (Section 2(b)(6))
-
Limited Eligibility: The bill does not apply to federal employees who continue to receive their basic pay during a lapse in appropriations. (Section 2(a)(2)(C))
-
No Debt Forgiveness: The act explicitly states that it does not grant forgiveness for any federally backed mortgage loan. (Section 2(b)(8))
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Low Income Households+6Good For Middle Class Households+6Good For Middle Aged+5Good For Veterans+5Good For High Income Households+2
- Social Issues And Justice
- Improves Affordable Housing+5Reduces Homelessness+3Improves Poverty Reduction+2
- Economy And Finance
- Improves Consumer Protection+4
- 11/7/2025
- Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- 3 Cosponsors added.
- Introduced in Senate
 Timothy Kaine
Democrat · Virginia
 Chris Van Hollen
Democrat · Maryland
 Mark Warner
Democrat · Virginia