Bill · S. 2003· Senate(119-S-2003)
Strengthening Benefit Plans Act of 2025
- Introduced
- 6/10/2025
- Last activity
- 6/10/2025 — Read twice and referred to the Committee on Finance.
- Sponsored by
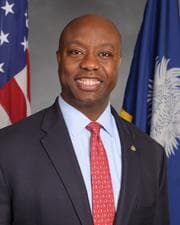
- Tim Scott
- Cosponsors
- - 3 - 0
- Introduced
- In Committee
What this bill would do
The Strengthening Benefit Plans Act of 2025 aims to amend the Internal Revenue Code regarding the movement of plan assets. Title I allows pension plans to transfer excess health assets to fund active employee benefits or voluntary employees' beneficiary associations. Title II permits employers to transfer surplus assets from a defined benefit plan to a qualified replacement defined contribution plan. These transfers are subject to specific requirements regarding benefit vesting and the prevention of benefit reductions. The bill includes various conforming amendments to existing laws like ERISA and the Internal Revenue Code. The provisions regarding health assets apply to taxable years after December 31, 2024, while retirement contribution provisions apply to plan years after December 31, 2025.
Yes· 3 of 5
Would people over 65 be better off under this?+5
The bill allows for the funding of active employee benefits and protects retirement asset transfers.
Would business owners be better off under this?+4
It provides employers with greater flexibility in managing surplus and excess assets within benefit plans.
Would retired people be better off under this?+4
The bill aims to protect benefit security through vesting and nonforfeitability requirements.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Funding Active Employee Benefits: Pension plans may transfer excess health assets to help fund active employee benefits or a voluntary employees' beneficiary association (Section 101(a)(1)).
-
Increased Benefit Security through Vesting: Transfers of excess health assets must meet specific vesting requirements to ensure stability for the participants (Section 101(a)(3)(A)(iv)).
-
Protection of Benefits for Replacement Plans: In the context of transferring surplus assets to a defined contribution plan, the law requires that no benefits under the replacement plan be reduced for a set period (Section 201(a)(4)).
-
Benefit Security through Nonforfeitability: When transferring surplus defined benefit plan assets, the bill requires that all benefits become nonforfeitable, similar to a plan termination (Section 201(a)(3)).
-
Transparency through Notice Requirements: Plan administrators are required to provide notice to participants and beneficiaries before certain transfers take place, including information about the amount to be transferred and the resulting pension benefits (Section 101(c)).
Potential Negative Impacts for People
-
Restrictions on Deductions for Employers: Employers are not allowed to take a tax deduction for the transfer of excess health assets or for certain benefits paid out of those assets (Section 101(a)(4)(A)).
-
Benefit Reduction Limitations: While intended to protect, the law imposes specific requirements that the applicable employer cost must not be materially less than previous years to maintain the arrangement (Section 101(a)(4)(B)(i)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Seniors+5Good For Business Owners+4Good For Retirees+4Good For Middle Class Households+3Good For Union Workers+2
- 6/10/2025
- Read twice and referred to the Committee on Finance.
- 3 Cosponsors added.
- Introduced in Senate
 Bill Cassidy
Republican · Louisiana
 Roger Marshall
Republican · Kansas
 Thomas Tillis
Republican · North Carolina