Bill · S. 1813· Senate(119-S-1813)
High-Quality Charter Schools Act
- Introduced
- 5/20/2025
- Last activity
- 3/19/2026 — Committee on Health, Education, Labor, and Pensions. Hearings held.
- Sponsored by
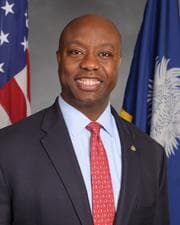
- Tim Scott
- Cosponsors
- - 3 - 0
- Introduced
- In Committee
What this bill would do
The High-Quality Charter Schools Act aims to amend the Internal Revenue Code of 1986. It introduces a tax credit for individuals who make qualified charitable contributions to certain charter school organizations. These contributions are intended for the creation or expansion of charter schools. The credit allows taxpayers to claim 75 percent of their qualified contributions, subject to specific limits. The bill also establishes rules regarding how organizations must spend these funds and sets a national volume cap for the credits.
Yes· 3 of 10
Does this make it easier to use public money at a school other than the local one?+7
By promoting charter school expansion through tax credits, the bill increases school choice options.
Would high-income households be better off under this?+5
The tax credit is highly beneficial for those with higher adjusted gross incomes capable of large donations.
Would people with substantial wealth be better off under this?+5
The credit provides a significant tax incentive for large charitable contributions.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Tax Relief for Donors: Individuals who are citizens or residents of the United States can receive a tax credit equal to 50 percent of their qualified contributions for the creation or expansion of charter schools (Section 25F(a)).
-
Support for High-Performing Schools: The bill provides a pathway for charter management organizations or schools that are in the highest 10 percent for student performance in their State to become eligible organizations (Section 25F(c)(2)(A)(ii)).
-
Increased School Opportunities: The credit is specifically intended for the creation or expansion of charter schools (Section 25F(c)(3)).
-
Freedom of Operation: The act is construed to allow eligible charter school organizations maximum freedom to provide for student needs without governmental control (Section 5(a)(2)).
Potential Negative Impacts for People
-
Contribution Limits: The tax credit is capped at either 10 percent of the taxpayer's adjusted gross income or $5,000, whichever is greater (Section 25F(b)).
-
Restrictions on Deductions: Individuals cannot take a charitable contribution deduction under section 170 for any contribution that is used to claim this tax credit (Section 25F(d)).
-
Credit Expiration: If a taxpayer has unused credits, they can only be carried forward for up to five years (Section 25F(e)(2)).
-
Program Caps: There is a nationwide volume cap of $5,000,000,000 for these tax credits, and credits are distributed on a first-come, first-serve basis (Section 4(a) and 4(b)).
-
Organizational Penalties: If an eligible charter school organization fails to meet the required expenditure amount—which involves spending the contributions before a specific deadline—future contributions to that organization may no longer be treated as qualified contributions (Section 4969(a) and (b)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Billionaires+5Good For High Income Households+5Good For High Net Worth Individuals+5Good For Students+5Good For Ultra High Net Worth Individuals+5Good For Children+4Good For Middle Class Households+3Good For Low Income Households+2
- Education And Technology
- Improves School Choice+7Increases Public School Funding+5
- 4/28/2026
- 1 Cosponsor added.
- 4/13/2026
- 1 Cosponsor added.
- 3/19/2026
- Committee on Health, Education, Labor, and Pensions. Hearings held.
- 6/4/2025
- 1 Cosponsor added.
- 5/20/2025
- Read twice and referred to the Committee on Finance.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Bill Cassidy
Republican · Louisiana
 Rick Scott
Republican · Florida
 Tommy Tuberville
Republican · Alabama