Bill · H.R. 9813· House(119-HR-9813)
To amend the Internal Revenue Code of 1986 to impose limitations on high-income taxpayers with large retirement account balances.
- Introduced
- 7/21/2026
- Last activity
- 7/21/2026 — Referred to the House Committee on Ways and Means.
- Sponsored by
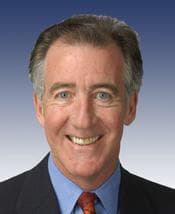
- Richard Neal
- Cosponsors
- None
- Introduced
- In Committee
What this bill would do
This bill proposes amendments to the Internal Revenue Code of 1986 to target high-income taxpayers with significant retirement account balances. It introduces a cap on annual contributions to individual retirement plans once a taxpayer's aggregate vested balances reach a specific dollar amount. Additionally, the bill increases minimum required distributions for these high-balance taxpayers. It also establishes an excise tax on contributions that exceed the new limits. These changes aim to regulate how much large retirement accounts can grow and how quickly funds must be distributed.
Yes· 3 of 4
Does this raise taxes on the highest earners?+7
The bill imposes new contribution limits and an excise tax on high-income taxpayers with large retirement account balances.
Does this make the government pay for what it commits to?+3
By accelerating the distribution of large retirement balances, the bill may increase near-term federal tax revenue.
Would retired people be better off under this?+3
The bill provides high-balance individuals with the right to elect immediate distributions from their accounts.
The opposite
Would high-income households be better off under this?-8
High-income earners face new limits on retirement contributions, increased required distributions, and higher withholding rates.
Who it would affect, and how
Potential Positive Impacts for People
-
Increased Minimum Required Distributions: High-income taxpayers with very large aggregate account balances will be required to take higher minimum distributions (Section 2(a)(1)).
-
Immediate Distribution Rights: Employees subject to the new distribution requirements can elect to receive distributions from their accounts in amounts they choose, rather than waiting for standard distribution schedules (Section 2(b)(1)).
-
Exception from Early Distribution Tax: Distributions taken to satisfy the new increased minimum requirements will not be subject to the 10 percent additional tax on early distributions (Section 2(b)(2)).
Potential Negative Impacts for People
-
Contribution Limitations: High-income taxpayers face limits on their annual contributions to individual retirement plans once their total vested balances exceed a specific threshold (Section 1(a)).
-
Excise Tax on Excess Contributions: An excise tax will be imposed on any annual contributions made to retirement plans that exceed the newly established limits (Section 1(b)(1)).
-
Increased Minimum Required Distributions: Taxpayers with large account balances will face an increase in the amount they are required to withdraw from their plans (Section 2(a)(1)).
-
Higher Withholding Rates: Distributions made under these new rules will be treated as nonperiodic distributions, resulting in a 37 percent withholding rate instead of 10 percent (Section 2(b)(3)(A)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Increases Wealthy Taxes+7Improves Fiscal Responsibility+3
- Demographic And Interest Groups
- Good For Retirees+3Good For High Income Households-8
- Social Issues And Justice
- Improves Poverty Reduction+2
- 7/21/2026
- Referred to the House Committee on Ways and Means.
- Introduced in House
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.