Bill · H.R. 9460· House(119-HR-9460)
Sustainable Homeownership Act
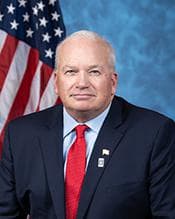
- Introduced
- 6/25/2026
- Last activity
- 6/25/2026 — Referred to the House Committee on Financial Services.
- Sponsored by
- Scott Fitzgerald
- Cosponsors
- None
- Introduced
- In Committee
What this bill would do
The Sustainable Homeownership Act aims to amend the regulatory and operational requirements for Freddie Mac and Fannie Mae. The bill introduces new requirements for the ownership of certain mortgage assets, including specific insurance or guarantee needs for high loan-to-value mortgages. It also establishes a return on equity range for these enterprises and creates a framework for risk-based capital requirements. Additionally, the act outlines a process for the enterprises to exit conservatorship through capital standards and stock sales. Finally, it establishes rules for transferring credit risk to a diversified pool of investors.
Yes· 3 of 8
Does this make housing cost less?+6
The bill directs securities toward supporting housing supply initiatives, including affordable and middle-income developments.
Does this reduce what the federal government owes?+5
The bill allows for obligations and securities to be dedicated to the purpose of deficit reduction.
Would households on low incomes be better off under this?+5
The bill allows for lower insurance or guarantee requirements for low-income mortgagors.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Refinancing Benefits: The Corporation may purchase conventional mortgages with high principal balances if the new mortgage reduces payment amounts, shortens the amortization term, or replaces a variable rate with a fixed rate for at least 60 months (Section 2(a)(1)(B)).
-
Support for Low-Income Borrowers: The Director of the Federal Housing Finance Agency may permit lower insurance or guarantee requirements for low-income mortgagors, defined as those with household incomes not more than 80 percent of the area median income (Section 2(a)(1)(B)(ii)).
-
Housing Supply Initiatives: Obligations and securities may be dedicated to supporting housing supply initiatives, including affordable and middle-income housing developments (Section 2(a)(2)).
-
Standardized Pricing for Mortgages: The Corporation is prohibited from varying the pricing or contractual terms of single-family residential mortgage acquisitions based on the size, charter type, or volume of business of the seller (Section 2(a)(g)(1)).
Potential Negative Impacts for People
-
Mortgage Ownership Restrictions: The bill implements limits on purchases of high loan-to-value mortgages, requiring specific insurance or guarantees for the portion of the unpaid principal balance in excess of 80 percent (Section 2(a)(1) and Section 2(b)(1)).
-
Prohibitions on Certain Mortgages: The Corporation may not purchase a single-family residential mortgage if it was originated in combination with a subordinate lien that provided access to a home equity line of credit that could exceed 80 percent of the property value (Section 2(a)(g)(3)).
-
Risk of Required Stock Sales: If an enterprise does not meet necessary capital standards, the Director may direct the enterprise to sell stock to meet those standards (Section 2(a)(8)(d)(2)(A)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Reduces National Debt+5Improves Fiscal Responsibility+4Improves Economic Growth+3Improves Consumer Protection+2
- Demographic And Interest Groups
- Good For Low Income Households+5Good For Middle Class Households+4
- Social Issues And Justice
- Improves Affordable Housing+6
- Governance And Ideology
- Improves Government Transparency+3
- 6/25/2026
- Referred to the House Committee on Financial Services.
- Introduced in House