Bill · H.R. 9064· House(119-HR-9064)
To amend the Internal Revenue Code of 1986 to temporarily increase the capital gains exclusion for any qualifying senior who sells a principal residence during a qualifying year, and for other purposes.
- Introduced
- 5/29/2026
- Last activity
- 5/29/2026 — Referred to the House Committee on Ways and Means.
- Sponsored by
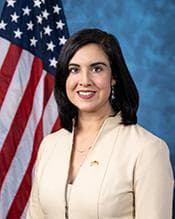
- Nicole Malliotakis
- Cosponsors
- - 1 - 0
- Introduced
- In Committee
What this bill would do
This bill proposes to amend the Internal Revenue Code of 1986 to temporarily raise the capital gains exclusion for selling a principal residence. The changes would apply to qualifying seniors who sell a qualifying residence between December 31, 2026, and January 1, 2031. A qualifying senior is defined as an individual at least 65 years old at the time of sale. A qualifying residence must be a principal residence owned for at least 25 years. The bill provides different exclusion amounts for single, married joint filers, and married individuals filing separately.
Yes· 3 of 4
Would people over 65 be better off under this?+8
Seniors aged 65 and older receive a significantly higher tax exclusion on the sale of their long-term primary residence.
Would retired people be better off under this?+8
The bill benefits retirees who meet the age and long-term ownership requirements by reducing their tax burden upon selling a home.
Does this cut the tax on profits from selling investments?+7
The bill increases the amount of capital gains that can be excluded from taxation when selling a principal residence for qualifying seniors.
The opposite
Does this reduce what the federal government spends?-2
By increasing tax exclusions, the bill reduces the total amount of tax revenue collected by the government.
Who it would affect, and how
Potential Positive Impacts for People
-
Increased Tax Exclusion for Seniors: The bill would allow qualifying seniors to exclude more of their capital gains from taxes when selling a long-term home. For single qualifying seniors, the exclusion would increase from $250,000 to $1,000,000 (Section 1, a, A, i).
-
Benefits for Married Couples: Married individuals who file joint returns and include a qualifying senior would see their exclusion amounts increased from $500,000 to $1,000,000 (Section 1, a, A, ii).
-
Benefits for Married Individuals Filing Separately: A qualifying senior who is married but files a separate return would see their exclusion amount increase from $250,000 to $500,000 (Section 1, a, A, iii).
Potential Negative Impacts for People
-
Time Limits on Benefits: The increased exclusion amounts are temporary and only apply to sales or exchanges occurring after December 31, 2026, and before January 1, 2031 (Section 1, a, A).
-
Ownership Requirements: To qualify for these higher exclusions, the residence must have been owned by the taxpayer for at least 25 years (Section 1, a, C).
-
Age Requirements: The increased exclusion is only available to those who are at least 65 years old on the date of the sale or exchange (Section 1, a, B).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Retirees+8Good For Seniors+8Good For High Income Households+5
- Economy And Finance
- Reduces Capital Gains Tax+7Reduces Government Spending-2
- 8/27/2026
- 1 Cosponsor added.
- 5/29/2026
- Referred to the House Committee on Ways and Means.
- Introduced in House
 Michael Lawler
Republican · New York