Bill · H.R. 7109· House(119-HR-7109)
Small Business Child Care Investment Act
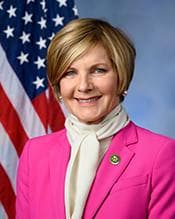
- Introduced
- 1/15/2026
- Last activity
- 1/15/2026 — Referred to the House Committee on Small Business.
- Sponsored by
- Susie Lee
- Cosponsors
- - 0 - 2
- Introduced
- In Committee
What this bill would do
The Small Business Child Care Investment Act aims to allow nonprofit child care providers to participate in certain Small Business Administration loan programs. It defines a "covered nonprofit child care provider" as a 501(c)(3) organization primarily engaged in childcare for children from birth to compulsory school age. These providers must comply with state licensing requirements and criminal background check standards for all employees and regular volunteers. To be eligible for loans over $500,000, these organizations must obtain a guarantee of timely payment from another person or entity. The bill also prohibits direct lending by the Administrator, requiring loans to be made in cooperation with financial institutions on a deferred basis. Finally, it requires the Small Business Administration to submit annual reports to Congress regarding these loans.
Yes· 3 of 7
Does this make it easier to run a small business?+6
The bill expands access to essential SBA loan programs for nonprofit child care providers by classifying them as small business concerns.
Would business owners be better off under this?+5
Nonprofit leaders will gain new avenues for financing their organizations through SBA 7(a) and 504 programs.
Does this protect the individual right to speak freely?+4
The bill protects organizations from being denied loan eligibility based on their association with entities performing First Amendment protected activities.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Access to Funding for Nonprofit Providers: By deeming covered nonprofit child care providers as "small business concerns," they can access loans and financings under section 7(a) of the Small Business Act and the 504 Program (Section 2(a)(B)(i) and Section 2(b)(2)(A)). This provides a way for these organizations to obtain capital for their operations.
-
Protection of First Amendment Activities: The bill includes a limitation that prevents the Administrator from denying loan eligibility based on an organization's association with entities whose activities are protected by the First Amendment (Section 2(a)(C) and Section 2(b)(3)).
Potential Negative Impacts for People
-
Financial Burdens for Large Loans: For any loan or financing exceeding $500,000, a covered nonprofit child care provider is required to obtain a guarantee of timely payment from another person or entity (Section 2(a)(B)(iii) and Section 2(b)(2)(C)). This could present a significant hurdle or additional cost for organizations seeking larger amounts of funding.
-
Restricted Lending Methods: The bill prohibits the Small Business Administration from making direct loans or entering into immediate participation agreements for these providers, requiring them to work through banks or other financial institutions on a deferred basis (Section 2(a)(B)(ii) and Section 2(b)(2)(B)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Improves Small Business Support+6Increases Job Creation+3
- Demographic And Interest Groups
- Good For Business Owners+5Good For Children+2Good For Women+1
- Governance And Ideology
- Improves Freedom Of Speech+4
- Social Issues And Justice
- Improves Childcare Affordability+2
- 7/13/2026
- 1 Cosponsor added.
- 1/15/2026
- Referred to the House Committee on Small Business.
- 1 Cosponsor added.
- Introduced in House
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Michael Lawler
Republican · New York
 Pete Stauber
Republican · Minnesota