Bill · H.R. 7044· House(119-HR-7044)
Energy Burden Tax Credit Act
- Introduced
- 1/13/2026
- Last activity
- 1/13/2026 — Referred to the House Committee on Ways and Means.
- Sponsored by
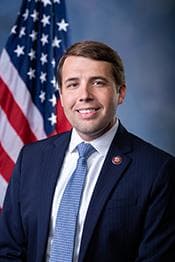
- Chris Pappas
- Cosponsors
- - 2 - 2
- Introduced
- In Committee
What this bill would do
This bill, titled the "Energy Burden Tax Credit Act," seeks to amend the Internal Revenue Code of 1986. It proposes the creation of a new energy burden credit for individuals. The credit is based on qualified energy expenses related to heating or cooling a taxpayer's principal residence. It allows a credit of 75 percent of these expenses that exceed 3 percent of the taxpayer's modified adjusted gross income. There are specific dollar and income limitations placed on the credit. The proposed credit is set to terminate after December 31, 2027.
Yes· 3 of 6
Would households on low incomes be better off under this?+5
The credit offers significant relief for energy expenses to those earning below the specified income thresholds.
Does this cut taxes for middle-income families?+5
The bill provides a tax credit for energy expenses to individuals earning up to $75,000 or $150,000 for joint returns.
Would middle-income households be better off under this?+3
The credit provides tax relief for energy costs to households earning up to $150,000 for joint returns.
The opposite
Does this reduce what the federal government spends?-2
The bill creates a new tax credit which reduces federal tax revenue.
Who it would affect, and how
Potential Positive Impacts for People
- Tax Credit for Energy Costs: Individuals can receive a credit equal to 75 percent of qualified energy expenses that exceed 3 percent of their modified adjusted gross income (Section 2(a)). This provides financial relief for fuel or electricity costs used to heat or cool a principal residence (Section 2(b)).
Potential Negative Impacts for People
-
Dollar Limitations: The credit is capped at a maximum of $1,500 for individuals or $3,000 for joint returns (Section 2(c)(1)).
-
Income Restrictions: Individuals with a modified adjusted gross income exceeding $75,000, or $150,000 for joint returns, are not eligible for the credit (Section 2(c)(2)).
-
Expiration of Benefit: The credit is temporary and will not be allowed for any taxable year beginning after December 31, 2027 (Section 2(c)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Low Income Households+5Good For Middle Class Households+3Good For Urban Residents+2
- Economy And Finance
- Reduces Middle Class Taxes+5Reduces Government Spending-2
- Social Issues And Justice
- Improves Poverty Reduction+3
- Environment Energy And Infrastructure
- Reduces Gas Prices+2
- 3/20/2026
- 1 Cosponsor added.
- 2/26/2026
- 1 Cosponsor added.
- 2/10/2026
- 1 Cosponsor added.
- 1/13/2026
- Referred to the House Committee on Ways and Means.
- 1 Cosponsor added.
- Introduced in House
 Michael Lawler
Republican · New York
 James Moylan
Republican · Guam
 Haley Stevens
Democrat · Michigan
 Eugene Vindman
Democrat · Virginia