Bill · H.R. 5975· House(119-HR-5975)
Appraisal Modernization Act
- Introduced
- 11/7/2025
- Last activity
- 11/7/2025 — Referred to the Committee on Financial Services, and in addition to the Committee on Rules, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned.
- Sponsored by
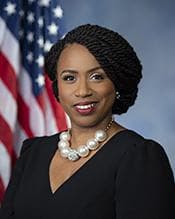
- Ayanna Pressley
- Cosponsors
- None
- Introduced
- In Committee
What this bill would do
This bill, known as the Appraisal Modernization Act, amends the Truth in Lending Act to give consumers the right to request a reconsideration of value or a subsequent appraisal. It sets clear rules for what counts as an unacceptable appraisal practice, such as using unsupported terms, inaccurate data, or references to crime rates. Creditors must provide a standard format for consumers to submit their requests and must keep all related documents in the loan file for seven years. If a creditor finds material deficiencies or evidence of discrimination, they must order a subsequent appraisal at their own expense. Additionally, the bill requires the Comptroller General to issue a public report to Congress assessing the feasibility of creating a national public appraisal database.
Yes· 3 of 26
Does this give people more protection from unfair business practices?+8
Establishes a formal, standardized consumer right to request reconsideration of value and requires lenders to cover subsequent appraisals for deficiencies or discrimination.
Would Black Americans be better off under this?+7
Directly addresses racial bias in home appraisals by banning crime rate references and enforcing penalties for discriminatory valuations.
Does this protect the right to fair treatment by the courts?+7
Provides mortgage applicants with a structured due process mechanism to challenge unfair or deficient home appraisals.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Consumers gain a clear, standardized process to request a reconsideration of value or a subsequent appraisal if they believe their appraisal report is unsupported, deficient, or discriminatory, as outlined in Section 2. This helps protect people from unfair home valuations.
-
Creditors are required to order a subsequent appraisal at their own expense if there are material deficiencies or evidence of discrimination that the original appraiser does not correct, as detailed in Section 2. This ensures that borrowers do not have to pay out of pocket to fix appraisal mistakes.
-
The bill explicitly bans appraisers from using references to crime rates or crime statistics and unsupported or subjective terms in their reports under Section 2. This prevents biased information from negatively impacting home values in specific communities.
Potential Negative Impacts for People
- Creditors must manage a detailed review and resolution procedure, provide written disclosures, and retain all related documentation for a 7-year period, as required in Section 2. These added administrative steps and record-keeping burdens could potentially slow down the mortgage loan process for applicants.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For African Americans+7Good For Hispanic Americans+6Good For Asian Americans+5Good For Low Income Households+5Good For Middle Class Households+5Good For Native Americans+5Good For Urban Residents+5Good For Immigrants+4Good For L G B T Q Community+3Good For Men+3Good For People With Disabilities+3Good For Rural Residents+3Good For Veterans+3Good For White Americans+3Good For Women+3Good For Young Adults+3Good For Middle Aged+2Good For Retirees+2Good For Seniors+2
- Governance And Ideology
- Improves Due Process+7Improves Government Transparency+6Increases Federal Power+3
- Social Issues And Justice
- Improves Racial Equity+7Improves Affordable Housing+5
- Economy And Finance
- Improves Consumer Protection+8Improves Small Business Support+2
- 11/7/2025
- Referred to the Committee on Financial Services, and in addition to the Committee on Rules, for a period to be subsequently determined by the Speaker, in each case for consideration of such provisions as fall within the jurisdiction of the committee concerned.
- Introduced in House
2 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.