Bill · H.R. 5402· House(119-HR-5402)
Credit Access and Inclusion Act of 2026
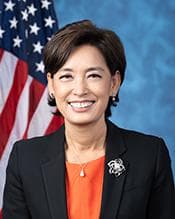
- Introduced
- 9/16/2025
- Last activity
- 9/1/2026 — Placed on the Union Calendar, Calendar No. 688.
- Sponsored by
- Young Kim
- Cosponsors
- - 0 - 2
- Introduced
- On Calendar
What this bill would do
The Credit Access and Inclusion Act of 2026 aims to amend the Fair Credit Reporting Act. It clarifies federal law regarding the reporting of certain full-file consumer credit information to consumer reporting agencies. The bill allows persons or the Secretary of Housing and Urban Development to furnish information about lease agreements and utility or telecommunications service payments. It also establishes specific rules for how energy utility firms report outstanding balances when payment plans are in place. Additionally, the Act includes a requirement for a GAO study on the impact of these changes.
Yes· 3 of 19
Would households on low incomes be better off under this?+6
Allows those without traditional loans to use rent and utility payments to improve credit scores.
Would people in their twenties and thirties be better off under this?+5
Young adults often lack credit history; rental and utility reporting helps them establish credit.
Would immigrants be better off under this?+5
New immigrants often lack US credit history; reporting basic payments helps them establish credit.
The opposite· 3 of 4
Does this protect people from being watched or searched?-3
Increases the volume of personal financial data shared with credit bureaus.
Does this give people more control over their personal data?-3
Expands the reporting of personal payment data to third-party credit agencies.
Does this protect the right to fair treatment by the courts?-2
Limits the liability of entities reporting this information, potentially making it harder for consumers to seek recourse.
Who it would affect, and how
Potential Positive Impacts for People
-
Protection of Credit Standing During Payment Plans: Under Section 2(a)(4), an energy utility firm cannot report a balance as late if the consumer has entered into a payment plan and is meeting the obligations of that plan. This could benefit individuals attempting to manage their debts through deferred payment or debt forgiveness programs.
-
Expanded Reporting of Positive Payment History: Section 2(a)(2) allows for the furnishing of information regarding payments made under lease agreements, including those with HUD-subsidized occupancy, as well as utility or telecommunications service contracts. This could help individuals demonstrate their payment performance to consumer reporting agencies.
Potential Negative Impacts for People
-
Increased Reporting of Debt Information: Section 2(a)(2) allows persons or the Secretary of Housing and Urban Development to furnish information relating to the performance of a consumer in making payments for lease agreements or utility and telecommunications services to a consumer reporting agency. This could result in more consumer data being shared with credit agencies.
-
Limitations on Reported Utility Information: Section 2(a)(3) limits information regarding utility usage to only that which relates to the payment of the service or terms of service, such as deposits or conditions for termination. This limits the scope of what can be reported regarding utility service usage.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Low Income Households+6Good For Immigrants+5Good For Students+5Good For Young Adults+5Good For African Americans+4Good For Hispanic Americans+4Good For Native Americans+4Good For Rural Residents+3Good For Urban Residents+3Good For Asian Americans+2Good For Middle Aged+2Good For Middle Class Households+2Good For Seniors+2Good For White Americans+2
- Social Issues And Justice
- Improves Affordable Housing+4Improves Poverty Reduction+3Improves Racial Equity+3Reduces Homelessness+2
- Governance And Ideology
- Improves Privacy Rights-3Improves Due Process-2
- Education And Technology
- Improves Data Privacy-3
- Economy And Finance
- Improves Economic Growth+2Improves Consumer Protection-2
- 9/1/2026
- Reported (Amended) by the Committee on Financial Services. H. Rept. 119-788.
- Placed on the Union Calendar, Calendar No. 688.
- 6/30/2026
- Committee Consideration and Mark-up Session Held
- Ordered to be Reported (Amended) by the Yeas and Nays: 28 - 23.
- 10/3/2025
- 1 Cosponsor added.
- 9/16/2025
- Referred to the House Committee on Financial Services.
- 1 Cosponsor added.
- Introduced in House
5 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Janelle Bynum
Democrat · Oregon
 Eugene Vindman
Democrat · Virginia