Bill · H.R. 3975· House(119-HR-3975)
Tax Fairness for Disaster Victims Act
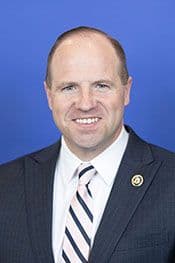
- Introduced
- 6/12/2025
- Last activity
- 6/12/2025 — Referred to the House Committee on Ways and Means.
- Sponsored by
- Timothy Kennedy
- Cosponsors
- - 7 - 0
- Introduced
- In Committee
What this bill would do
The Tax Fairness for Disaster Victims Act aims to amend the Internal Revenue Code of 1986. It introduces a lookback rule for individuals affected by certain federally declared disasters. This rule allows taxpayers to use their income from the previous year to determine certain tax credits if their current income has dropped. This applies specifically to those whose principal place of abode was in a disaster area during the specified disaster period. The bill addresses how earned income and social security taxes are substituted for credit determination purposes.
Yes· 3 of 5
Would households on low incomes be better off under this?+4
The lookback rule specifically assists those whose income drops, which often impacts low-income households.
Does this improve help for people hit by a disaster?+4
The bill provides financial relief to those suffering from federally declared disasters.
Would middle-income households be better off under this?+3
Provides tax credit protection for those whose earnings decrease due to disaster events.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Tax Credit Protection: For a qualified individual whose earned income is less than the previous year due to a disaster, they can substitute the previous year's income to determine credits allowed under section 32 and section 24(d) (Section 2, paragraph 1A).
-
Social Security Tax Substitution: If a taxpayer's social security taxes in the disaster year are less than the previous year, they can use the previous year's social security tax amount to determine the credit allowed under section 24(d) (Section 2, paragraph 1B).
-
Support for Families on Joint Returns: In the case of a joint return, the benefits apply if either spouse is a qualified individual, using the sum of both spouses' income and taxes from the preceding year (Section 2, paragraph 3).
Potential Negative Impacts for People
- Election Requirement: The benefits are not automatic; a qualified individual must elect the application of this subsection in such a manner as the Secretary may provide (Section 2, paragraph 1).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Low Income Households+4Good For Middle Class Households+3
- Environment Energy And Infrastructure
- Improves Disaster Relief And F E M A+4
- Economy And Finance
- Reduces Middle Class Taxes+3
- Social Issues And Justice
- Improves Poverty Reduction+3
- 6/12/2025
- Referred to the House Committee on Ways and Means.
- 7 Cosponsors added.
- Introduced in House
 Nanette Barragán
Democrat · California
 Judy Chu
Democrat · California
 Jared Huffman
Democrat · California
 Eleanor Norton
Democrat · District of Columbia
 Joe Neguse
Democrat · Colorado
 Rashida Tlaib
Democrat · Michigan
 Jill Tokuda
Democrat · Hawaii