Bill · H.R. 3186· House(119-HR-3186)
Universal Savings Account Act of 2025
- Introduced
- 5/5/2025
- Last activity
- 5/5/2025 — Referred to the House Committee on Ways and Means.
- Sponsored by
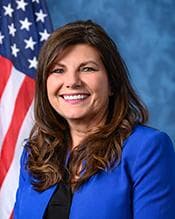
- Diana Harshbarger
- Cosponsors
- - 1 - 0
- Introduced
- In Committee
What this bill would do
This bill, titled the "Universal Savings Account Act of 2025," proposes to amend the Internal Revenue Code of 1986 to establish Universal Savings Accounts. These accounts are defined as trusts created for the exclusive benefit of an individual. The bill sets specific rules for contributions, which must be made in cash and stay within certain limits. It also establishes guidelines for trustees, such as banks or other approved persons. Additionally, the act dictates how these accounts are treated regarding taxes, distributions, and death.
Yes· 3 of 12
Would middle-income households be better off under this?+6
The tax-exempt nature of the accounts provides significant benefits for middle-class wealth accumulation.
Does this cut taxes for middle-income families?+5
The bill creates tax-exempt savings accounts that allow individuals to grow wealth without taxation on distributions.
Would people in middle age be better off under this?+4
This provides a tool for middle-aged individuals to save more effectively for the future.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Tax Exemptions: Universal Savings Accounts are exempt from taxation under the subtitle, and distributions are generally not includible in gross income (Section 530A(a), Section 530A(c)(2)(A)).
-
Spousal Protections: If an account holder dies, a surviving spouse can acquire the interest in the account and continue to be treated as the account holder (Section 530A(e)(1)).
-
Inflation Adjustments: The bill includes provisions to increase contribution limits and the $25,000 cap based on cost-of-living adjustments to account for inflation (Section 530A(c)(1)(A)(iii), Section 530A(c)(1)(B)(ii)).
Potential Negative Impacts for People
-
Contribution Limits: There are strict limits on how much can be contributed to these accounts in a calendar year (Section 530A(c)(1)).
-
Taxation on Excess Contributions: Net income attributable to excess contributions is includible in the account holder's gross income for the taxable year in which the contribution was made (Section 530A(c)(2)(B)).
-
Account Termination Upon Death: If the account holder is not a surviving spouse, all amounts in the account are treated as distributed on the date of death, and the account ceases to be a Universal Savings Account (Section 530A(e)(2)).
-
Investment Restrictions: The bill prohibits the use of trust funds for investing in life insurance contracts (Section 530A(b)(5)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Middle Class Households+6Good For Middle Aged+4Good For Retirees+4Good For Seniors+4Good For High Income Households+3Good For Young Adults+3Good For Low Income Households+2Good For High Net Worth Individuals+1
- Economy And Finance
- Reduces Middle Class Taxes+5Reduces Capital Gains Tax+4Improves Economic Growth+3
- Social Issues And Justice
- Improves Poverty Reduction+2
- 5/26/2026
- 1 Cosponsor added.
- 5/5/2025
- Referred to the House Committee on Ways and Means.
- Introduced in House
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Michael Cloud
Republican · Texas