Bill · H.R. 1778· House(119-HR-1778)
American Innovation Act of 2025
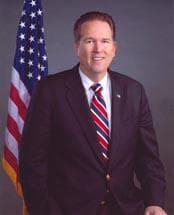
- Introduced
- 3/3/2025
- Last activity
- 3/3/2025 — Referred to the House Committee on Ways and Means.
- Sponsored by
- Vern Buchanan
- Cosponsors
- - 18 - 0
- Introduced
- In Committee
What this bill would do
The American Innovation Act of 2025 aims to amend the Internal Revenue Code of 1986 to encourage new business innovation. It simplifies how businesses can deduct start-up and organizational costs through an election process. Under this plan, taxpayers can deduct a specific amount of these expenditures in the year the business begins. Any remaining costs would be handled through amortization over a 180-month period. The bill also includes provisions regarding the preservation of net operating losses and tax credits during ownership changes.
Yes· 3 of 5
Does this make it easier to run a small business?+7
The bill provides practical tax relief for new businesses through immediate deductions and protection of losses during ownership changes.
Would business owners be better off under this?+7
The bill specifically benefits those starting new businesses by allowing them to deduct costs more quickly.
Does this cut taxes for small businesses?+6
The bill allows for an immediate deduction of up to $20,000 for start-up and organizational expenditures.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Immediate Deduction for Start-ups: Taxpayers can elect to deduct a specific amount of start-up and organizational expenditures in the year their active trade or business begins (Section 2(a)(1)(A)). This provides a direct financial benefit at the start of a business.
-
Inflation Protection: The $20,000 and $120,000 deduction thresholds are subject to inflation adjustments starting after December 31, 2026 (Section 2(a)(1)(A)(3)). This ensures the benefits maintain their value over time as the cost of living changes.
-
Flexibility During Business Closure: If a taxpayer completely liquidates a partnership or corporation, or disposes of a trade or business, they may be able to deduct start-up expenditures that were not previously allowed (Section 2(a)(c)).
-
Protection of Losses During Ownership Changes: The bill creates exceptions for net operating loss carryforwards and unused general business credits that arise during a "start-up period" (Section 3(a) and 3(b)). This helps preserve certain financial benefits when a business undergoes an ownership change.
Potential Negative Impacts for People
-
Limits on Immediate Deductions: The deduction for start-up and organizational expenditures is capped at $20,000 (Section 2(a)(1)(A)(ii)). Any amount exceeding this, or exceeding the $120,000 threshold, must be amortized over a 180-month period rather than being deducted all at once.
-
Restrictions on Loss Preservation: The preservation of start-up losses and credits depends on a continuity of business requirement, meaning the new owner must continue the trade or business for a 2-year period (Section 3(a)(F)).
-
Timing Restrictions: Certain provisions, such as the inflation adjustments and specific transition rules, do not apply to businesses that begin before certain dates in 2026 (Section 2(a)(3) and Section 3(a)(G)(i)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Improves Small Business Support+7Reduces Small Business Taxes+6Improves Economic Growth+4Increases Job Creation+3
- Demographic And Interest Groups
- Good For Business Owners+7
- 3/24/2026
- 1 Cosponsor added.
- 3/16/2026
- 1 Cosponsor added.
- 3/3/2026
- 4 Cosponsors added.
- 2/23/2026
- 4 Cosponsors added.
- 2/20/2026
- 1 Cosponsor added.
- 2/10/2026
- 1 Cosponsor added.
- 3/18/2025
- 1 Cosponsor added.
- 3/3/2025
- Referred to the House Committee on Ways and Means.
- 5 Cosponsors added.
- Introduced in House
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Don Bacon
Republican · Nebraska
 Earl Carter
Republican · Georgia
 Mike Carey
Republican · Ohio
 Ron Estes
Republican · Kansas
 Charles Fleischmann
Republican · Tennessee
 Mike Kelly
Republican · Pennsylvania
 David Kustoff
Republican · Tennessee
 Jennifer Kiggans
Republican · Virginia
 Michael Lawler
Republican · New York
 Carol Miller
Republican · West Virginia
 Blake Moore
Republican · Utah
 Max Miller
Republican · Ohio
 Nathaniel Moran
Republican · Texas
 Ryan Mackenzie
Republican · Pennsylvania
 Adrian Smith
Republican · Nebraska
 Claudia Tenney
Republican · New York
 Daniel Webster
Republican · Florida
 Rudy Yakym
Republican · Indiana