Bill · S. 798· Senate(119-S-798)
Capital Gains Inflation Relief Act of 2025
- Introduced
- 2/27/2025
- Last activity
- 2/27/2025 — Read twice and referred to the Committee on Finance.
- Sponsored by
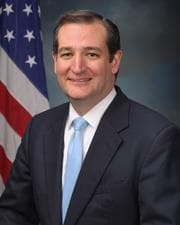
- Ted Cruz
- Cosponsors
- - 1 - 0
- Introduced
- In Committee
What this bill would do
The Capital Gains Inflation Relief Act of 2025 aims to amend the Internal Revenue Code of 1986 regarding how gains or losses are calculated. It introduces the concept of an "indexed basis" for certain assets held for more than three years. This indexing uses the gross domestic product deflator to adjust the basis of an asset for inflation. Covered assets include common stock in C corporations, certain foreign corporation stock, digital assets, and specific tangible property. The adjustments are designed to substitute the original adjusted basis with an inflation-adjusted one. This change applies to assets acquired after December 31, 2025.
Yes· 3 of 4
Would high-income households be better off under this?+5
High-income individuals often hold significant capital assets like stocks and property that would benefit from this inflation indexing.
Does this cut the tax on profits from selling investments?+5
The bill allows taxpayers to increase the basis of certain assets using the GDP deflator to account for inflation, thereby reducing the taxable capital gain.
Would people over 65 be better off under this?+4
Seniors holding long-term assets like stock or property would benefit from inflation-adjusted basis calculations.
The opposite
Is this likely to slow the rise in prices?-1
By adjusting asset basis through the GDP deflator, the bill addresses the impact of inflation on capital gains rather than reducing inflation itself.
Who it would affect, and how
Potential Positive Impacts for People
-
Inflation Relief on Asset Gains: For taxpayers holding certain assets for more than three years, the law allows the use of an indexed basis instead of the adjusted basis to determine gain or loss (Section 2(a)(1)). This helps account for inflation by increasing the basis of the asset based on the gross domestic product defator (Section 2(c)).
-
Inclusion of Digital Assets: The definition of an "indexed asset" specifically includes digital assets that are recorded on a cryptographically secured distributed ledger and designed for economic or access rights (Section 2(b)(1)(B) and 2(b)(3)).
-
Benefits for Investment Entities: The adjustment is allowed for qualified investment entities, which include regulated investment companies and real estate investment trusts (Section 2(e)(1)(A)).
-
Pass-Through Benefits: For partnerships, S corporations, and common trust funds, the adjustment made at the entity level is passed through to the partners, shareholders, or participants (Section 2(f)).
Potential Negative Impacts for People
-
Documentation Burden: The indexing of an asset only applies if the taxpayer has written documentation of the original purchase price paid or incurred to acquire that asset (Section 2(a)(3)).
-
Exclusion of Depreciation Benefits: Deductions for depreciation, depletion, and amortization are determined without regard to the inflation indexing (Section 2(a)(2)).
-
Restrictions on Risk-Reducing Transactions: If a taxpayer enters into a transaction that substantially reduces the risk of loss from holding an asset, that asset is not treated as an indexed asset for that period (Section 2(d)(1)).
-
Limitations on Transfers: The Secretary of the Treasury has the authority to disallow part or all of the adjustment if a person transfers property with the principal purpose of securing or increasing the inflation adjustment (Section 2(h)).
-
Restrictions on Related Person Dispositions: The indexing rules do not apply to sales or other dispositions of property between related persons, unless the basis in the hands of the transferee is a substituted basis (Section 2(g)(1)).
-
Loss Determination Limits: The indexing adjustment is not taken into account when determining the amount of any loss on a sale or exchange of an interest in a partnership, S corporation, or common trust fund (Section 2(f)(4)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For High Income Households+5Good For Business Owners+4Good For Seniors+4
- Economy And Finance
- Reduces Capital Gains Tax+5Reduces Inflation-1
- 2/27/2025
- Read twice and referred to the Committee on Finance.
- 1 Cosponsor added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Thomas Tillis
Republican · North Carolina