Bill · S. 608· Senate(119-S-608)
IRS MATH Act of 2025
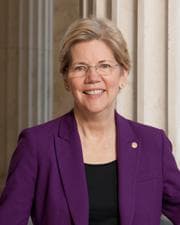
- Introduced
- 2/18/2025
- Last activity
- 2/18/2025 — Read twice and referred to the Committee on Finance. (text: CR S613)
- Sponsored by
- Elizabeth Warren
- Cosponsors
- - 0 - 1
- Introduced
- In Committee
What this bill would do
The "Internal Revenue Service Math and Taxpayer Help Act of 2025" aims to amend the Internal Revenue Code regarding math and clerical error notices. This bill requires the IRS to provide more detailed and specific information when notifying taxpayers of such errors. It mandates that notices include a comprehensive description of the error in plain language and an itemized computation of adjustments. The bill also requires specific formatting for the date by which a taxpayer can request an abatement. Additionally, it establishes a pilot program involving the use of certified or registered mail for these notices.
Yes· 3 of 26
Does this make what the government does easier for the public to see?+5
The bill requires the IRS to provide specific, itemized, and plain-language explanations of tax errors to taxpayers.
Would people with disabilities be better off under this?+4
The requirement for plain language and multiple ways to request abatements increases accessibility.
Would households on low incomes be better off under this?+3
Increased transparency and clearer abatement procedures help taxpayers understand and contest errors regardless of income.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Increased Clarity and Understanding: The bill requires the IRS to describe math or clerical errors in "comprehensive, plain language," including the type of error, the relevant section of the title, the nature of the error, and the specific line on the tax return where the error occurred (Section 2(a)(1)(B)(i)(II)).
-
Detailed Financial Transparency: Notices must include an "itemized computation" of adjustments to items such as adjusted gross income, taxable income, deductions, credits, and total tax (Section 2(a)(1)(B)(i)(III)).
-
Improved Accessibility to Help: The bill requires that notices include a "telephone number for the automated phone transcript service" (Section 2(a)(1)(B)(i)(IV)).
-
Clear Deadlines for Taxpayer Action: The date by which a taxpayer may request to abate an assessment must be displayed in "bold, font size 14" and placed "immediately next to the taxpayer's address on page 1 of the notice" (Section 2(a)(1)(B)(i)(V)).
-
Better Communication of Abatements: If a tax abatement is determined, the Secretary must send a notice that describes the abatement in "comprehensive, plain language" and provides an "itemized computation of any adjustments" (Section 2(b)(C)).
-
Established Methods for Requesting Abatements: The Secretary must provide procedures for taxpayers to request an abatement "in writing, electronically, by telephone, or in person" (Section 2(d)).
Potential Negative Impacts for People
- Wait Time for Improvements: The new requirements for these notices do not take effect until "12 months after the date of the enactment of this Act" (Section 2(c)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For People With Disabilities+4Good For African Americans+3Good For Asian Americans+3Good For Billionaires+3Good For Business Owners+3Good For Farmers+3Good For Gun Owners+3Good For High Income Households+3Good For High Net Worth Individuals+3Good For Hispanic Americans+3Good For Immigrants+3Good For L G B T Q Community+3Good For Low Income Households+3Good For Men+3Good For Middle Class Households+3Good For Native Americans+3Good For Retirees+3Good For Rural Residents+3Good For Students+3Good For Ultra High Net Worth Individuals+3Good For Union Workers+3Good For Urban Residents+3Good For Veterans+3Good For White Americans+3Good For Women+3
- Governance And Ideology
- Improves Government Transparency+5
- 2/18/2025
- Read twice and referred to the Committee on Finance. (text: CR S613)
- 1 Cosponsor added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Bill Cassidy
Republican · Louisiana