Bill · S. 5216· Senate(119-S-5216)
Senior Accessible Housing Tax Credit Act of 2026
- Introduced
- 8/3/2026
- Last activity
- 8/3/2026 — Read twice and referred to the Committee on Finance.
- Sponsored by
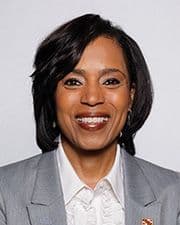
- Angela Alsobrooks
- Cosponsors
- - 1 - 0
- Introduced
- In Committee
What this bill would do
The Senior Accessible Housing Tax Credit Act of 2026 proposes an amendment to the Internal Revenue Code of 1986. It seeks to establish a new tax credit for eligible individuals to cover qualified accessible housing expenses. This credit is intended for individuals who have reached age 60 and are not nonresident aliens. The expenses covered include various home modifications designed to improve safety and independence. The credit is subject to specific dollar limitations and income thresholds. These changes would apply to taxable years beginning after December 31, 2026.
Yes· 3 of 8
Would people over 65 be better off under this?+8
The bill directly provides financial support for seniors to improve their home accessibility.
Would retired people be better off under this?+8
The bill provides significant financial assistance to retirees for home modifications.
Would people with disabilities be better off under this?+7
The bill assists in funding accessibility modifications essential for people with disabilities.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Financial assistance for home accessibility: Eligible individuals can receive a credit against their taxes for expenses related to making home modifications like installing wheelchair ramps, widening doorways, or installing grab bars (Section 2(c)(1)).
-
Support for independent living: The bill allows for modifications that the Secretary determines would improve an individual's ability to live safely and independently (Section 2(c)(1)(K)).
-
Coverage of labor costs: The credit includes expenses for labor costs related to the onsite preparation, assembly, or original installation of qualified property (Section 2(c)(1)).
-
Inflation protection: Starting after 2027, the dollar amounts for the credit and income thresholds are adjusted for inflation based on the cost-of-living adjustment (Section 2(d) and Section 2(f)).
Potential Negative Impacts for People
-
Caps on total credit amount: The credit is limited to a maximum of $10,000 per taxpayer for any taxable year (Section 2(d)(1)).
-
Income restrictions: The amount of the credit is reduced if a taxpayer's modified adjusted gross income exceeds certain thresholds, which are $200,000 for joint returns, $150,000 for head of household, and $100,000 for others (Section 2(d)(2)).
-
Prevention of multiple benefits: Taxpayers cannot claim another credit or deduction for the same expenses used to claim this credit, and the basis of the property must be reduced by the amount of the credit (Section 2(e)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Retirees+8Good For Seniors+8Good For People With Disabilities+7Good For Middle Class Households+5Good For Low Income Households+3
- Social Issues And Justice
- Improves Affordable Housing+5Improves Disability Rights+5
- Economy And Finance
- Reduces Middle Class Taxes+5
- 8/3/2026
- Read twice and referred to the Committee on Finance.
- 1 Cosponsor added.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Kirsten Gillibrand
Democrat · New York