Bill · S. 4761· Senate(119-S-4761)
Tax Court Parity Act
- Introduced
- 6/11/2026
- Last activity
- 6/11/2026 — Read twice and referred to the Committee on Finance.
- Sponsored by
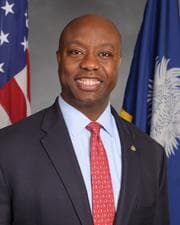
- Tim Scott
- Cosponsors
- - 0 - 1
- Introduced
- In Committee
What this bill would do
This bill is called the Tax Court Parity Act. It amends the Internal Revenue Code of 1986. The main goal is to clarify the authority of the Tax Court to order relief from a judgment or order. It allows the Tax Court to correct clerical mistakes, oversights, and omissions. It also sets grounds and timelines for a party to be relieved from a final judgment or order.
Yes
Does this protect the right to fair treatment by the courts?+4
The bill enhances due process by explicitly granting the Tax Court authority to correct clerical mistakes and relieve parties from final judgments under just terms.
Does this make what the government does easier for the public to see?+3
The legislation clearly establishes procedures and grounds for relief from Tax Court judgments, improving the transparency of judicial operations.
Does this shorten or soften prison sentences?+2
The bill clarifies the Tax Court's authority to order relief from judgments or orders, providing a fairer legal process for correcting errors.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Section 2 adding subsection (e)(1)(A) allows the Tax Court to fix clerical mistakes or mistakes from oversight and omissions in a judgment, order, or record on its own or on a motion. This is positive because it gives a common-sense way to fix simple errors without unnecessary hassle.
-
Section 2 adding subsection (e)(2) allows the Tax Court to relieve a party or its legal representative from a final judgment or order for reasons like mistake, surprise, newly discovered evidence, fraud, or when justice so requires. This is positive because it protects everyday people if new evidence comes to light or if an opposing party commits fraud or misrepresentation.
Potential Negative Impacts for People
- Section 2 adding subsection (e)(3)(A)(ii) requires that a motion for relief based on mistake, inadvertence, surprise, excusable neglect, newly discovered evidence, or fraud must be made not later than 1 year after the entry of the judgment or order. This could be viewed as a negative burden because it sets a strict 1-year deadline that might cut off people who discover issues too late.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Governance And Ideology
- Improves Due Process+4Improves Government Transparency+3
- Social Issues And Justice
- Improves Criminal Sentencing Reform+2
- 6/11/2026
- Read twice and referred to the Committee on Finance.
- 1 Cosponsor added.
- Introduced in Senate
2 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Maggie Hassan
Democrat · New Hampshire