Bill · S. 3151· Senate(119-S-3151)
National Flood Insurance Program Automatic Extension Act of 2025
- Introduced
- 11/6/2025
- Last activity
- 11/6/2025 — Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- Sponsored by
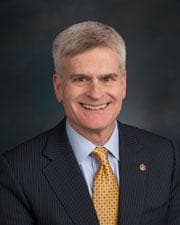
- Bill Cassidy
- Cosponsors
- - 1 - 0
- Introduced
- In Committee
What this bill would do
This bill is called the National Flood Insurance Program Automatic Extension Act of 2025. It changes the National Flood Insurance Act of 1968 to allow the National Flood Insurance Program to extend automatically. This means the program can continue to issue and renew insurance contracts and pay claims even if it reaches its termination date. The extension lasts until the end of the fiscal year following the termination year, unless a new law extends or repeals it first.
Yes· 3 of 30
Does this improve help for people hit by a disaster?+5
Directly ensures that flood insurance claims can be paid and policies renewed during disaster recovery.
Would households on low incomes be better off under this?+4
Prevents catastrophic financial loss for those who cannot afford to rebuild without insurance.
Would middle-income households be better off under this?+3
Ensures continued availability of essential flood insurance for their primary assets.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Continued Insurance Coverage: The bill allows the Administrator to enter into, issue, renew contracts, and keep existing flood insurance coverage in force (Section 2(c)(2)(A)-(B)). This ensures people can still get or keep flood insurance.
-
Consistent Claim Payments: The bill ensures the program can continue to pay claims and service policies (Section 2(c)(2)(C)). This means people who suffer flood damage can still receive the money they are owed.
-
Operational Stability: The bill allows the program to carry out administrative functions and continue operating (Section 2(c)(2)(D)). This keeps the program running without interruption.
Potential Negative Impacts for People
- There are no negative impacts for people explicitly listed in the provided text.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Low Income Households+4Good For Business Owners+3Good For Farmers+3Good For Middle Class Households+3Good For Rural Residents+3Good For High Income Households+2Good For Middle Aged+2Good For Retirees+2Good For Seniors+2Good For Urban Residents+2Good For African Americans+1Good For Asian Americans+1Good For Billionaires+1Good For Children+1Good For High Net Worth Individuals+1Good For Hispanic Americans+1Good For Native Americans+1Good For Ultra High Net Worth Individuals+1Good For Veterans+1Good For White Americans+1Good For Young Adults+1
- Economy And Finance
- Improves Consumer Protection+3Improves Small Business Support+2Improves Economic Growth+1
- Environment Energy And Infrastructure
- Improves Disaster Relief And F E M A+5Improves Rural Development+1
- Social Issues And Justice
- Improves Affordable Housing+2Improves Poverty Reduction+1Reduces Homelessness+1
- Governance And Ideology
- Improves Interstate Commerce+1
- 11/10/2025
- 1 Cosponsor added.
- 11/6/2025
- Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 John Kennedy
Republican · Louisiana