Bill · S. 1839· Senate(119-S-1839)
Generating Retirement Ownership through Long-Term Holding
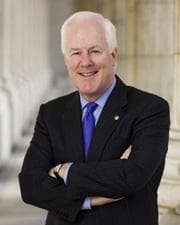
- Introduced
- 5/21/2025
- Last activity
- 5/21/2025 — Read twice and referred to the Committee on Finance.
- Sponsored by
- John Cornyn
- Cosponsors
- - 2 - 0
- Introduced
- In Committee
What this bill would do
This bill, titled the "Generating Retirement Ownership through Long-Term Holding" Act, proposes an amendment to the Internal Revenue Code of 1986. It seeks to allow individuals to defer paying taxes on capital gain dividends received from regulated investment companies if those dividends are automatically reinvested into more shares through a dividend reinvestment plan. Under this proposal, the gains are not recognized immediately but are instead taxed later. This recognition occurs either when the individual sells or redeems their stock or upon the individual's death. The bill also establishes specific rules for determining holding periods for these reinvested shares.
Yes· 3 of 10
Would people over 65 be better off under this?+5
The bill facilitates long-term wealth accumulation through reinvested dividends, which can benefit retirees.
Would high-income households be better off under this?+5
The ability to defer capital gains recognition is particularly beneficial for those with significant investment portfolios.
Would people with substantial wealth be better off under this?+5
High-net-worth individuals can utilize this to compound wealth more efficiently through tax deferral.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Tax Deferral on Reinvested Dividends: Under Section 2(a), individuals would not have to recognize gains immediately when a capital gain dividend is automatically reinvested in additional shares via a dividend reinvestment plan. This allows for the deferral of tax recognition.
-
Determined Holding Period: Section 2(a)(2)(3) states that a taxpayer's holding period for shares acquired through these reinvested dividends will be treated as one year and a day as of the date the shares are acquired.
Potential Negative Impacts for People
-
Future Tax Obligations upon Sale: According to Section 2(a)(2)(A)(i), the deferred gain must be recognized when the individual sells or redeems their stock in the distributing company.
-
Taxation upon Death: Section 2(a)(2)(A)(ii) specifies that any portion of the total gain not recognized prior to death shall be recognized upon the death of the taxpayer and included in their gross income for that taxable year.
-
Exclusions for Certain Taxpayers: Section 2(c) notes that these benefits will not apply to individuals who have a deduction under section 151 allowable to another taxpayer, nor will they apply to estates or trusts.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Billionaires+5Good For High Income Households+5Good For High Net Worth Individuals+5Good For Retirees+5Good For Seniors+5Good For Ultra High Net Worth Individuals+5Good For Middle Class Households+4
- Economy And Finance
- Reduces Capital Gains Tax+4Reduces Middle Class Taxes+3Improves Economic Growth+2
- 7/13/2026
- 1 Cosponsor added.
- 4/30/2026
- 1 Cosponsor added.
- 5/21/2025
- Read twice and referred to the Committee on Finance.
- Introduced in Senate
One bill Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.