Bill · S. 113· Senate(119-S-113)
Promoting New Bank Formation Act of 2025
- Introduced
- 1/16/2025
- Last activity
- 1/16/2025 — Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- Sponsored by
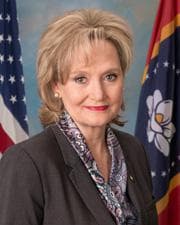
- Cindy Hyde-Smith
- Cosponsors
- - 1 - 0
- Introduced
- In Committee
What this bill would do
The Promoting New Bank Formation Act of 2025 seeks to assist de novo financial institutions and rural community banks. It requires federal banking agencies to create a 3-year phase-in period for new institutions to meet federal capital requirements. The bill also establishes an 8 percent Community Bank Leverage Ratio for rural community banks during their first three years. Additionally, it amends the Home Owners' Loan Act to include agricultural loans for federal savings associations. Finally, the act mandates a study by federal agencies to understand why de novo bank formation has slowed and how to promote it in underserved areas.
Yes· 3 of 11
Would farmers be better off under this?+5
The bill expands the authority of federal savings associations to provide secured or unsecured agricultural loans.
Would people in rural areas be better off under this?+5
The bill specifically provides relief and leverage ratio support for rural community banks to combat branch closures.
Does this invest in rural communities?+5
The bill specifically targets rural community banks to provide better financial access to rural areas.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Capital Standard Relief: Financial institutions will receive a 3-year phase-in period to meet federal capital requirements, starting from when their deposit insurance becomes effective (Section 4).
-
Business Plan Flexibility: During the initial 3-year period, financial institutions can request to deviate from their agency-approved business plans, and if the agency fails to act on the request within 30 days, it is deemed approved (Section 5).
-
Support for Rural Community Banks: Rural community banks will benefit from a Community Bank Leverage Ratio of 8 percent during their first three years, with agencies authorized to phase this in with even lower percentages during the first two years (Section 6).
-
Expanded Loan Authority: Federal savings associations will have the authority to provide secured or unsecured loans for agricultural purposes (Section 7).
Potential Negative Impacts for People
- No specific negative impacts or burdens are explicitly stated in the provided text.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Farmers+5Good For Rural Residents+5Good For Business Owners+4Good For African Americans+2Good For Low Income Households+2
- Economy And Finance
- Improves Small Business Support+4Increases Job Creation+3
- Environment Energy And Infrastructure
- Improves Rural Development+5
- Social Issues And Justice
- Improves Poverty Reduction+2Improves Racial Equity+2
- Governance And Ideology
- Improves Government Transparency+1
- 1/27/2025
- 1 Cosponsor added.
- 1/16/2025
- Read twice and referred to the Committee on Banking, Housing, and Urban Affairs.
- Introduced in Senate
 Tim Sheehy
Republican · Montana