Bill · H.R. 9529· House(119-HR-9529)
NO PROFIT Act
- Introduced
- 6/29/2026
- Last activity
- 6/29/2026 — Referred to the House Committee on Ways and Means.
- Sponsored by
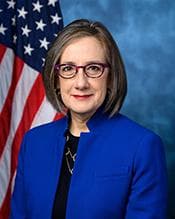
- Andrea Salinas
- Cosponsors
- None
- Introduced
- In Committee
What this bill would do
The "NO PROFIT Act" amends the Internal Revenue Code of 1986 to tax net capital gains earned while serving as President of the United States. It imposes a 100 percent tax on qualified net capital gains for any taxable year in which the individual served as President. Assets not held in a qualified blind trust are subject to these rules, including a "mark to market" requirement where gains or losses are recognized as if the asset were sold at the end of the taxable year. This act applies to taxable years beginning after December 31, 2024.
Yes
Does this make what the government does easier for the public to see?+5
Discourages personal financial gain from office, indirectly promoting integrity and reducing conflict of interest.
Does this raise taxes on the highest earners?+5
Imposes a 100% tax on capital gains for the President, who is typically a high-net-worth individual.
Does this reduce what the federal government owes?+1
Increases federal revenue through a high tax on presidential capital gains, though the impact is minimal due to the small number of taxpayers.
The opposite· 3 of 5
Does this cut the tax on profits from selling investments?-10
Significantly increases the capital gains tax to 100% for the President.
Would high-income households be better off under this?-5
Specifically targets the highest possible income bracket (the President) with a prohibitive tax.
Would people with substantial wealth be better off under this?-5
Creates a significant financial penalty for capital gains for the President.
Who it would affect, and how
Potential Positive Impacts for People
- Taxing Presidential Gains: The bill imposes a 100 percent tax on qualified net capital gains for those serving as President, as stated in Section 2(a)(1). This ensures that net capital gains accrued while in office are taxed at the full amount.
Potential Negative Impacts for People
-
High Tax Burden on the President: Section 2(a)(1) requires a tax equal to 100 percent of qualified net capital gains, which removes the entirety of those specific gains from the individual.
-
Mark to Market Requirements: Under Section 2(a)(2), the President must recognize gain or loss on capital assets not in a qualified blind trust as if they were sold for fair market value on the last business day of the taxable year.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Billionaires-5Good For High Income Households-5Good For High Net Worth Individuals-5Good For Ultra High Net Worth Individuals-5
- Governance And Ideology
- Improves Government Transparency+5
- Economy And Finance
- Increases Wealthy Taxes+5Reduces National Debt+1Reduces Capital Gains Tax-10
- 6/29/2026
- Referred to the House Committee on Ways and Means.
- Introduced in House