Bill · H.R. 9490· House(119-HR-9490)
Bank Failure Accountability Act
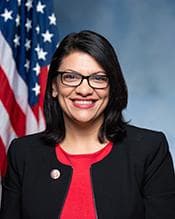
- Introduced
- 6/25/2026
- Last activity
- 6/25/2026 — Referred to the House Committee on Financial Services.
- Sponsored by
- Rashida Tlaib
- Cosponsors
- - 3 - 0
- Introduced
- In Committee
What this bill would do
The Bank Failure Accountability Act requires large financial institutions with over $1 billion in assets to set up deferment funds for senior employee compensation. A portion of pay for these employees is held back based on how much it exceeds seven times the median employee's pay. These funds are used to pay civil or criminal fines levied against the institution. If a depository institution or credit union fails, the funds are used to ensure depositors do not lose their deposits. After a specific deferment period, any remaining funds are paid back to the employee.
Yes· 3 of 8
Does this give people more protection from unfair business practices?+6
The bill strengthens protections for depositors by ensuring bank collapse liabilities and fines are paid out of executive compensation funds first.
Would households on low incomes be better off under this?+4
Protects everyday account holders from bearing the costs of financial institution collapses and corporate misconduct.
Would middle-income households be better off under this?+4
Protects middle-class deposits and savings from being lost when financial institutions fail.
The opposite· 3 of 4
Would the very wealthiest people be better off under this?-6
Top earners and executives at large financial institutions face significant restrictions and clawbacks on their compensation.
Would billionaires be better off under this?-6
Ultra-wealthy senior banking executives are targeted to cover corporate fines and bank failure losses.
Would people with substantial wealth be better off under this?-5
High-net-worth senior executives at large financial institutions are directly impacted by deferred and potentially canceled compensation.
Who it would affect, and how
Potential Positive Impacts for People
-
Protection for Depositors: If a credit union or depository institution fails, the deferment fund is used to ensure depositors do not lose their deposits, with these funds being used before the Deposit Insurance Fund or the National Credit Union Share Insurance Fund (Section 3(c)(2)).
-
Accountability for Misconduct: The bill requires that civil or criminal fines against a financial institution be paid first out of the senior employees' deferment funds (Section 3(c)(1)).
Potential Negative Impacts for People
-
Loss of Compensation for Senior Employees: Senior employees may have at least 50 percent of their compensation that exceeds seven times the median employee's pay deferred (Section 3(b)(1)).
-
Cancellation of Pay: Compensation deferred in the fund may be canceled if the fund does not have enough money to repay the employee after the deferment period (Section 3(d)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Improves Consumer Protection+6Improves Fiscal Responsibility+3Improves Economic Growth+2
- Demographic And Interest Groups
- Good For Low Income Households+4Good For Middle Class Households+4Good For Retirees+3Good For Seniors+3Good For Billionaires-6Good For Ultra High Net Worth Individuals-6Good For High Net Worth Individuals-5Good For High Income Households-4
- Governance And Ideology
- Increases Federal Power+2
- 6/25/2026
- Sponsor introductory remarks on measure. (CR H4251)
- Referred to the House Committee on Financial Services.
- 3 Cosponsors added.
- Introduced in House
2 bills Congress.gov lists as related to this one — companions in the other chamber, earlier versions, and bills this one absorbed or was folded into.
 Al Green
Democrat · Texas
 Stephen Lynch
Democrat · Massachusetts
 Summer Lee
Democrat · Pennsylvania