Bill · H.R. 9166· House(119-HR-9166)
Student Loan Refinancing Act of 2026
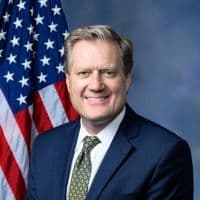
- Introduced
- 6/4/2026
- Last activity
- 6/4/2026 — Referred to the House Committee on Education and Workforce.
- Sponsored by
- Michael Turner
- Cosponsors
- - 1 - 2
- Introduced
- In Committee
What this bill would do
This bill, known as the Student Loan Refinancing Act of 2026, requires the Secretary of Education to set up a program allowing borrowers to refinance certain Federal student loans. Under Section 460A, borrowers can apply to refinance Federal Direct Loans and FFEL Program loans to secure fixed interest rates. The legislation ensures that refinancing does not extend loan repayment periods or add origination fees. It also limits borrowers to refinancing a loan no more than twice during a ten-year period. Finally, the bill directs the government to conduct an outreach campaign to inform eligible borrowers about the new refinancing options.
Yes· 3 of 11
Would students be better off under this?+7
Directly assists current and former students holding federal loans by offering lower fixed interest rates and safeguarding forgiveness progress.
Would people in their twenties and thirties be better off under this?+6
Young adults burdened with recent higher education loans benefit directly from fixed interest rate refinancing options.
Does this reduce what student borrowers owe or repay?+6
Provides a structured mechanism for eligible borrowers to refinance Federal student loans into fixed interest rates.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Access to Fixed Interest Rates: Under Section 460A(a) and Section 460A(c), borrowers are given the opportunity to apply to refinance certain Federal student loans to obtain new fixed interest rates. This is positive because it can potentially lower the interest burden on individuals managing student debt.
-
No Extra Fees or Extended Timelines: According to Section 460A(d)(2) and Section 460A(d)(3), refinancing a loan will not result in the application of an origination fee, nor will it automatically extend the duration of the repayment period. This protects people from extra charges and keeps them on their current timeline to pay off their debt.
-
Preservation of Past Progress for Certain Repayment Plans: Under Section 455(e)(9) and Section 493C(f), borrowers who refinance loans before July 1, 2028, will have their past monthly payments toward income-contingent and income-based repayment counted alongside payments made on the new refinanced loan. This ensures individuals do not lose the progress they have already made toward loan forgiveness programs.
-
Information Campaigns: Section 460A(e) requires the Secretary and the Bureau of Consumer Financial Protection to run a campaign alerting borrowers and providing consumer information about the availability of refinancing. This helps ensure people are actually aware of the options they have to potentially help their financial situation.
Potential Negative Impacts for People
-
Limits on Refinancing Frequency: Under Section 460A(d)(4), a loan may not be refinanced under this section more than twice during a 10-year period. This creates a regulatory burden and restricts individuals from adjusting their loans more frequently if financial circumstances change.
-
Disadvantage for Public Service Loan Count on FFEL Loans: According to Section 455(m)(3)(B), for a Federal Direct Loan refinanced under Section 460A that was originally an FFEL loan, only monthly payments made after the refinancing date may be counted toward the Public Service Loan Forgiveness program. This means borrowers with these specific loans lose credit for any past public service payments they made prior to refinancing.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Students+7Good For Young Adults+6Good For Middle Class Households+5Good For Middle Aged+4Good For Low Income Households+3
- Economy And Finance
- Improves Consumer Protection+4Improves Economic Growth+3
- Education And Technology
- Improves Student Loan Relief+6
- Governance And Ideology
- Improves Government Transparency+2Increases Federal Power+2
- Social Issues And Justice
- Improves Poverty Reduction+2
- 6/4/2026
- Referred to the House Committee on Education and Workforce.
- 3 Cosponsors added.
- Introduced in House
 Lloyd Doggett
Democrat · Texas
 Brian Fitzpatrick
Republican · Pennsylvania
 Donald Norcross
Democrat · New Jersey