Bill · H.R. 8328· House(119-HR-8328)
Defining Dealer Act
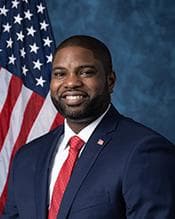
- Introduced
- 4/16/2026
- Last activity
- 4/16/2026 — Referred to the House Committee on Financial Services.
- Sponsored by
- Byron Donalds
- Cosponsors
- None
- Introduced
- In Committee
What this bill would do
This bill, known as the Defining Dealer Act, seeks to amend the Securities Exchange Act of 1934. It specifically aims to provide a new definition for the term "dealer." The amendment changes how a dealer is defined regarding the buying and selling of securities for their own account. It also includes provisions for the treatment of certain orders and judgments during a transition period. These changes are set to take effect 30 days after the Act is enacted.
Yes
Would business owners be better off under this?+4
The bill provides relief by vacating legal actions and orders that no longer align with the new, narrower definition of a dealer.
Would high-income households be better off under this?+3
The refined definition of dealer and the vacating of certain orders may provide regulatory relief to high-net-worth market participants.
The opposite
Does this give people more protection from unfair business practices?-4
The bill limits the definition of a dealer and requires the vacating of existing legal orders and judgments, which may reduce regulatory oversight and consumer protections.
Does this make what the government does easier for the public to see?-2
The requirement to vacate prior legal orders and judgments may reduce the transparency of historical regulatory enforcement actions.
Who it would affect, and how
Potential Positive Impacts for People
-
Clarification of Dealer Definition: The bill amends Section 3(a)(5) to define a dealer as someone engaging in transactions by buying from customers or selling to customers for their own account, while specifically excluding certain security-based swaps. This provides a specific legal definition for the term (Section 2(a)(1)).
-
Vacating Certain Actions: The bill provides a mechanism where a court or the Securities and Exchange Commission must vacate covered actions, such as orders or judgments, that would not have been entered under the new definition. This applies to both actions entered during a transition period and those entered prior to the enactment of the Act (Section 2(b)(1) and Section 2(b)(2)).
Potential Negative Impacts for People
- Mandatory Vacating of Orders: The bill requires the applicable court or the Securities and Exchange Commission to vacate "covered actions," which include orders or judgments or consent orders, if they would not have been entered under the new dealer definition (Section 2(b)(1) and Section 2(b)(2)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Business Owners+4Good For High Income Households+3
- Economy And Finance
- Improves Consumer Protection-4
- Governance And Ideology
- Improves Government Transparency-2
- 4/16/2026
- Referred to the House Committee on Financial Services.
- Introduced in House