Bill · H.R. 8314· House(119-HR-8314)
OPTIONS Act
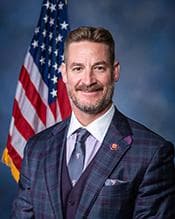
- Introduced
- 4/15/2026
- Last activity
- 4/15/2026 — Referred to the House Committee on Ways and Means.
- Sponsored by
- W. Steube
- Cosponsors
- - 0 - 1
- Introduced
- In Committee
What this bill would do
This bill, known as the "OPTIONS Act," seeks to amend the Internal Revenue Code of 1986. It proposes the creation of "qualified benefit options plans" offered by employers to current and former employees. Under these plans, employees can choose how to allocate employer contributions among various qualified benefits. However, participants cannot choose to receive cash or other taxable benefits instead of these qualified benefits. The changes are intended to apply to taxable years beginning after December 31, 2025.
Yes· 3 of 4
Would people over 65 be better off under this?+5
The bill explicitly extends the benefit of qualified benefit options plans to former and retired employees.
Would retired people be better off under this?+5
The bill includes former and retired employees in the definition of eligible participants for qualified benefit options plans.
Does this make college cost less?+5
The bill permits the allocation of employer contributions into qualified educational assistance programs.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Choice in Benefit Allocation: Participants in a qualified benefit options plan may elect to allocate employer contributions among different qualified benefits (Section 2(a)(b)(1)(A)). This provides employees with more control over how their employer-provided benefits are distributed.
-
Tax-Free Treatment of Selections: No amount will be included in the gross income of a participant simply because they chose among the benefits available in the plan (Section 2(a)(a)). This ensures that the act of choosing between benefits does not create a new tax burden for the employee.
-
Variety of Qualified Benefits: The bill defines qualified benefits to include non-elective employer contributions, health reimbursement arrangements, health savings accounts, and qualified educational assistance programs (Section 2(a)(b)(2)). This allows employees to direct funds toward various essential needs like healthcare or education.
Potential Negative Impacts for People
-
Restrictions on Cash Payments: Participants may not elect to receive cash or any other taxable benefit instead of the qualified benefits listed in the plan (Section 2(a)(b)(1)(B)). This means employees cannot opt for liquid cash instead of the specific benefit options provided by the employer.
-
Rules for Highly Compensated Participants: The bill notes that rules similar to those in section 125 will apply to highly compensated participants and key employees (Section 2(a)(c)). This implies there may be certain limitations or exceptions placed on specific groups of employees.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Retirees+5Good For Seniors+5Good For Middle Class Households+4
- Education And Technology
- Improves College Affordability+5
- 4/15/2026
- Referred to the House Committee on Ways and Means.
- 1 Cosponsor added.
- Introduced in House
 Suzan DelBene
Democrat · Washington