Bill · H.R. 7922· House(119-HR-7922)
Small Business Dependent Care FSA Opportunity Act
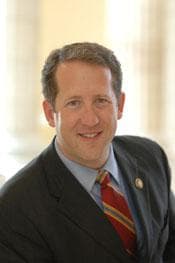
- Introduced
- 3/12/2026
- Last activity
- 3/12/2026 — Referred to the House Committee on Ways and Means.
- Sponsored by
- Adrian Smith
- Cosponsors
- - 1 - 1
- Introduced
- In Committee
What this bill would do
The Small Business Dependent Care FSA Opportunity Act proposes to give certain small employers a tax credit for the costs of starting up dependent care flexible spending plans. This credit covers qualified startup costs, including plan administration and employee education. The credit is available for the first credit year and the two following taxable years. It is limited to a specific dollar amount based on the number of non-highly compensated employees or a maximum cap. To qualify, the employer must not have had a similar plan for the same employees in the previous three years.
Yes· 3 of 11
Would business owners be better off under this?+7
Directly provides a tax credit for startup costs of these benefit plans.
Does this make it easier to run a small business?+6
Directly supports small employers by reducing the financial burden of implementing dependent care plans.
Does this make child care cost less?+5
Encourages small businesses to offer dependent care FSAs, which helps employees pay for childcare with pre-tax dollars.
The opposite
Does this reduce what the federal government owes?-1
The introduction of a new tax credit slightly reduces federal tax revenue.
Who it would affect, and how
Potential Positive Impacts for People
-
Financial help for small employers: Eligible employers can receive a tax credit for "qualified startup costs," which include expenses for establishing, administering, or educating employees about dependent care flexible spending plans (Sec. 2(d)(1)).
-
Support for non-highly compensated employees: The credit amount can be calculated based on $250 for each employee who is not a highly compensated employee and is eligible to participate in the plan (Sec. 2(b)(1)(B)(i)).
Potential Negative Impacts for People
-
Limited time frame: The credit is only available for the "first credit year and each of the 2 taxable years immediately following," after which the credit amount is zero (Sec. 2(b)(1) and (2)).
-
Strict eligibility limits: Employers are not eligible for the credit if they or a controlled group maintained a similar dependent care flexible spending plan for the same employees during the 3-taxable year period before the first credit year (Sec. 2(c)(2)).
-
Capped benefits: The credit is limited to the greater of $500 or the lesser of $250 per eligible non-highly compensated employee, with an absolute maximum cap of $5,000 (Sec. 2(b)(1)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Business Owners+7Good For Low Income Households+4Good For Middle Class Households+4Good For Women+4Good For Middle Aged+3Good For Children+2
- Economy And Finance
- Improves Small Business Support+6Reduces Small Business Taxes+4Improves Economic Growth+1Reduces National Debt-1
- Social Issues And Justice
- Improves Childcare Affordability+5Improves Poverty Reduction+1
- 3/12/2026
- Referred to the House Committee on Ways and Means.
- 2 Cosponsors added.
- Introduced in House
 Danny Davis
Democrat · Illinois
 Nathaniel Moran
Republican · Texas