Bill · H.R. 7770· House(119-HR-7770)
Hearing Aid Assistance Tax Credit Act
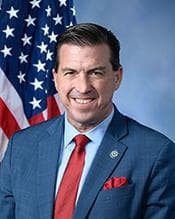
- Introduced
- 3/3/2026
- Last activity
- 3/3/2026 — Referred to the House Committee on Ways and Means.
- Sponsored by
- Kevin Mullin
- Cosponsors
- - 1 - 1
- Introduced
- In Committee
What this bill would do
This bill, titled the "Hearing Aid Assistance Tax Credit Act," proposes an amendment to the Internal Revenue Code of 1986. It seeks to allow a tax credit for individuals who purchase qualified hearing aids. The credit applies to amounts paid that are not covered by insurance or other compensation, up to a limit of $1,000. To qualify, the hearing aid must meet specific federal regulations and be intended for the taxpayer or their dependents. There are specific income limits and a rule that the election can only be made once every five years.
Yes· 3 of 8
Would people over 65 be better off under this?+5
The tax credit assists seniors who may require hearing aids for better quality of life.
Would people with disabilities be better off under this?+5
The credit directly supports people with hearing disabilities by offsetting the cost of hearing aids.
Would retired people be better off under this?+5
Retirees are a demographic that likely benefits from the hearing aid tax credit.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Tax Credit for Hearing Aids: Individuals can receive a credit against their income tax for the purchase of qualified hearing aids, which can cover costs not compensated by insurance (Section 2, subsection a).
-
Support for Dependents: The benefit extends to hearing aids intended for use by an individual for whom the taxpayer is allowed a deduction for personal exemptions (Section s, subsection c, part 2).
Potential Negative Impacts for People
-
Income Limitations: Individuals with a modified adjusted gross income exceeding $300,000 for a joint return or head of household, or exceeding $150,000 for other individuals, are not allowed to claim the credit (Section 2, subsection b, part 1).
-
Frequency Restrictions: An individual can only elect to use this credit once every five years (Section 2, subsection d).
-
Restriction on Uncompensated Costs: The credit only applies to amounts not already compensated by insurance or otherwise (Section 2, subsection a).
-
Prohibition on Double Benefits: No credit is allowed for any expense for which a deduction or credit is already allowed under another provision of the chapter (Section 2, subsection e).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For People With Disabilities+5Good For Retirees+5Good For Seniors+5Good For Middle Class Households+4Good For Low Income Households+2
- Healthcare
- Improves Healthcare Access+5
- Social Issues And Justice
- Improves Disability Rights+5
- Economy And Finance
- Reduces Middle Class Taxes+3
- 4/27/2026
- 1 Cosponsor added.
- 3/30/2026
- 1 Cosponsor added.
- 3/3/2026
- Referred to the House Committee on Ways and Means.
- Introduced in House
 Adelita Grijalva
Democrat · Arizona
 Jennifer Kiggans
Republican · Virginia