Bill · H.R. 6458· House(119-HR-6458)
Electronic Filing Improvement and Logistical Efficiency Act of 2025
- Introduced
- 12/4/2025
- Last activity
- 12/4/2025 — Referred to the House Committee on Ways and Means.
- Sponsored by
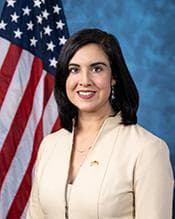
- Nicole Malliotakis
- Cosponsors
- - 1 - 2
- Introduced
- In Committee
What this bill would do
The Electronic Filing Improvement and Logistical Efficiency Act of 2025 aims to improve how employment taxes are filed by moving away from paper. It requires the IRS to create a fully automated electronic process for filing and paying all employment tax requirements within one year. To encourage this shift, the bill provides a $1,000 tax credit for employers who switch to electronic filing. However, the bill also introduces a $250 user fee for those who continue to submit paper returns. This legislation seeks to overcome structural and behavioral obstacles to digital filing.
Yes· 3 of 8
Does this cut taxes for small businesses?+5
The bill provides a tax credit of up to $2,000 for employers who transition to electronic filing.
Would business owners be better off under this?+5
The bill provides specific tax credits to incentivize and reward the transition to electronic filing.
Does this make it easier to run a small business?+4
The bill offers financial incentives and streamlines the tax filing process for employers.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
-
Increased efficiency for employers: The IRS must create a fully automated electronic process for filing and paying all employment tax requirements, specifically focusing on the adjusted employer's quarterly Federal tax return or claim for refund (Form 941-X) (Section 3).
-
Financial incentive to switch to digital: Employers can receive a $1,000 credit for the calendar quarter in which they first make all their returns and payments electronically (Section 4(a)(1)).
-
Continued support for digital transition: Employers can elect to receive an additional $1,000 credit for one calendar quarter in the year following their initial switch to electronic filing (Section 4(a)(2)).
-
Protection for those with limited access: Exceptions to both the credit recapture and the paper filing user fee are available for employers who lack ready access to broadband or face geographic barriers, such as those in rural areas, or for those facing emergency situations (Section 4(c)(2)(A) and Section 5(b)(1)(C-D)).
-
Protection for victims of crime: Exceptions to the paper filing user fee are available for recent victims of identity theft or cybercrimes (Section 5(b)(1)(E)).
Potential Negative Impacts for People
-
Financial penalty for continuing paper filing: The Secretary is required to impose a $250 user fee on any quarterly or annual return submitted by means other than electronic filing (Section 5(a)).
-
Risk of losing previous credits: If an employer receives an electronic filing credit but then fails to make a subsequent return or payment electronically, the tax for that subsequent quarter will be increased by the amount of the credit previously allowed (Section 4(c)(1)(A)).
-
Loss of future credit eligibility: If an employer's credit is recaptured because they failed to file electronically, they are not allowed to receive any more electronic filing credits in subsequent quarters (Section 4(c)(1)(B)).
-
Exclusion of government entities: The electronic filing tax credit is not available to the United States Government, any State government, or any of their political subdivisions or agencies (Section 4(e)(2)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Reduces Small Business Taxes+5Improves Small Business Support+4Improves Economic Growth+2
- Demographic And Interest Groups
- Good For Business Owners+5Good For Rural Residents+3
- Environment Energy And Infrastructure
- Improves Rural Development+2
- Education And Technology
- Improves Internet Access+1
- Governance And Ideology
- Improves Government Transparency+1
- 5/15/2026
- 1 Cosponsor added.
- 12/4/2025
- Referred to the House Committee on Ways and Means.
- 2 Cosponsors added.
- Introduced in House
 Joseph Morelle
Democrat · New York
 Nathaniel Moran
Republican · Texas
 Thomas Suozzi
Democrat · New York