Bill · H.R. 6295· House(119-HR-6295)
The Working for Tips Tax Relief Act of 2025
- Introduced
- 11/25/2025
- Last activity
- 11/25/2025 — Referred to the House Committee on Ways and Means.
- Sponsored by
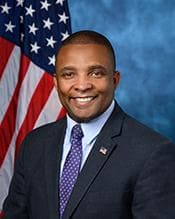
- Donald Davis
- Cosponsors
- - 1 - 0
- Introduced
- In Committee
What this bill would do
This bill, known as "The Working for Tips Tax Relief Act of 2025," aims to amend the Internal Revenue Code of 1986. It seeks to permanently exclude certain reported tips from gross income for workers in eligible service sectors to support low- and moderate-income earners. The legislation allows for a deduction of qualified tips, subject to specific income limits and caps. It includes provisions for annual living wage indexing and requires the Secretary to evaluate the impact on workforce participation. The tax exclusion is intended to apply to taxable years beginning after December 31, 2025, and expire on December 31, 2028. Following expiration, a pilot program will be established to examine the potential benefits of extending these exemptions permanently.
Yes· 3 of 7
Would households on low incomes be better off under this?+6
Low-income service workers benefit from the exclusion of tips from their taxable gross income.
Does this cut taxes for middle-income families?+5
The bill allows a deduction for qualified tips up to $35,000, providing tax relief for service workers in the middle-income range.
Would middle-income households be better off under this?+4
Middle-income earners in eligible service sectors receive tax relief on their tip income up to the specified caps.
The opposite
Would high-income households be better off under this?-2
The bill explicitly excludes individuals with adjusted gross incomes above $75,000 or $150,000 from receiving the full benefit.
Does this reduce what the federal government spends?-2
The tax exclusion reduces federal tax revenue, which may slightly increase the deficit.
Who it would affect, and how
Potential Positive Impacts for People
-
Support for Low- and Moderate-Income Earners: The bill is designed to better support workers in eligible service sectors by excluding certain reported tips from gross income (Section 2(a)).
-
Tax Relief via Deductions: Workers can claim a deduction for qualified tips received during the taxable year, which includes cash tips or those received under tip-sharing arrangements (Section 2(a) and Section 2(d)(3)).
-
Income-Based Adjustments: The Secretary is tasked with reviewing national and regional living wage estimates annually to potentially adjust the exclusion or eligibility thresholds (Section 2(c)).
-
Accessibility for Non-Itemizers: The bill amends the tax code to allow the deduction for those who do not itemize their deductions (Section 2(b)).
Potential Negative Impacts for People
-
Deduction Caps: The amount allowed as a deduction is limited to a maximum of $35,000 for any taxable year (Section 2(b)(1)).
-
Income Restrictions: The tax exclusion is reduced as income increases and will not apply at all to individuals with an adjusted gross income over $75,000, or $150,000 for joint returns (Section 2(b)(2)(A)).
-
Strict Filing Requirements for Married Couples: For married individuals, the exclusion only applies if both the taxpayer and their spouse file a joint return (Section 2(f)).
-
Identification Requirements: No deduction is allowed unless the taxpayer includes their social security number on their tax return (Section 2(e)(1)).
-
Specific Business Exclusions: The exclusion does not apply if the trade or business is a specified service trade or business (Section 2(d)(2)(B)).
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Demographic And Interest Groups
- Good For Low Income Households+6Good For Middle Class Households+4Good For Urban Residents+2Good For High Income Households-2
- Economy And Finance
- Reduces Middle Class Taxes+5Improves Economic Growth+2Reduces Government Spending-2
- Social Issues And Justice
- Improves Poverty Reduction+3
- Governance And Ideology
- Improves Government Transparency+1
- 10/9/2026
- 1 Cosponsor added.
- 11/25/2025
- Referred to the House Committee on Ways and Means.
- Introduced in House
 Darren Soto
Democrat · Florida