Bill · H.R. 10431· House(119-HR-10431)
U.S. Innovation and Global Competitiveness Act of 2026
- Introduced
- 9/16/2026
- Last activity
- 9/16/2026 — Referred to the House Committee on Ways and Means.
- Sponsored by
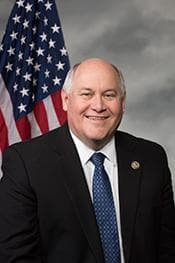
- Ron Estes
- Cosponsors
- None
- Introduced
- In Committee
What this bill would do
H.R. 10431, titled the U.S. Innovation and Global Competitiveness Act of 2026, changes several rules in the Internal Revenue Code regarding the taxation of international entities. It modifies deductions for foreign-derived intangible income and net controlled foreign corporation tested income, changes the base erosion minimum tax, and alters foreign tax credit limitation baskets. The bill also adjusts the carryover of net controlled foreign corporation tested losses, repeals certain foreign tax credit haircuts, and applies foreign-source dividend deductions to controlled foreign corporations. Additionally, it eliminates the inclusion of specific foreign base company income, exempts certain corporations from subpart F inclusions for United States property investments, and sets special rules for transfers of intangible property. Finally, it addresses services performed in the United States Virgin Islands, repeals a business interest limitation modification, treats the research credit as a specified credit for all taxpayers, and requires regulations to prevent duplicative charges for research and development expenditures.
Yes· 3 of 5
Does this cut taxes for small businesses?+6
The bill expands access to the research credit for a wider range of taxpayers, potentially lowering tax burdens for smaller businesses engaged in research.
Does this make it easier to run a small business?+5
Extending the research credit eligibility beyond just eligible small businesses helps support innovative smaller enterprises.
Would business owners be better off under this?+5
Business owners and corporate taxpayers benefit from expanded research credit access and modified international tax provisions.
The opposite
No question was scored the opposite.
Who it would affect, and how
Potential Positive Impacts for People
- Section 15: The bill treats the research credit as a specified credit for all taxpayers for the purposes of the general business credit, by amending Section 38(c)(4)(B)(ii) and striking paragraph (5). This change removes the restriction limiting this benefit only to eligible small businesses, which could allow a wider range of taxpayers to utilize the research credit.
Potential Negative Impacts for People
- Section 3: The bill amends Section 59A to make changes to the base erosion minimum tax and provides specific exceptions for payments subject to sufficient foreign tax or specific types of services. Depending on how these rules are applied, individuals or groups could face increased tax burdens or complex compliance requirements related to cross-border payments.
Groups and Interests Ranking
Every group the model scored this bill for, from -10 to +10. Hover a score for the reason it gave.
- Economy And Finance
- Reduces Small Business Taxes+6Improves Small Business Support+5Improves Economic Growth+3
- Demographic And Interest Groups
- Good For Business Owners+5
- Education And Technology
- Increases Scientific Research Funding+5
- 9/16/2026
- Referred to the House Committee on Ways and Means.
- Introduced in House